Goodman NZ raises FY27 guidance as warehouse leasing gathers pace

Goodman NZ has raised its FY27 Cash Earnings guidance after stronger leasing activity helped lift operating earnings and profit in the first half. The result also exposes a structural wrinkle: revenue fell 40.5% after the Highbrook portfolio shift, even as net profit rose 26.9%.
- FY27 Cash Earnings per stapled share guidance lifted to around 6% growth
- Net profit increased 26.9% to NZ$78.4 million
- Revenue fell 40.5% to NZ$88.5 million after the Highbrook structure change
- Portfolio occupancy reached 97.2%, with 18.9% rental uplift on new leases
- 18.1 million stapled shares bought back at an average NZ$1.95
 Add us as a preferred source on Google
Guidance rises as leasing supports earnings
Goodman NZ (NZX:GNZ) has raised its full-year Cash Earnings per stapled share guidance to around 6% above FY26, after leasing momentum helped produce a stronger first-half operating result. Operating earnings after tax rose 5.6% to NZ$69.5 million for the six months ended 30 September 2026, while Cash Earnings per stapled share increased 5.0% to 4.19 cents.
The headline numbers are more complicated than the guidance upgrade suggests. Revenue fell 40.5% to NZ$88.5 million, largely because the Highbrook Partnership has changed how income is reported: property income previously recognised directly by Goodman NZ is now reflected through its share of the partnership's operating earnings and fee income. Statutory profit nevertheless rose 26.9% to NZ$78.4 million, helped by lower net interest costs, property valuation gains and the partnership contribution.
Industrial leasing creates rental upside
Leasing was the clearest operating support. Goodman NZ secured new or revised terms across 107,745 square metres of stabilised space, achieving an 18.9% rental uplift on new leases and an average new lease term of 6.9 years. Occupancy stood at 97.2%, with a weighted average lease term of five years, while like-for-like net property income grew 5.2%.
The portfolio also carried potential rent reversion of 19.2% to market at 30 September, or 16.5% excluding vacancy. That is not an immediate earnings benefit, but it indicates where future rent reviews and leasing activity could support income if occupiers continue accepting higher rents. The company said customer decisions remain protracted, even as enquiry levels have begun to improve.
Auckland developments move from pipeline to delivery
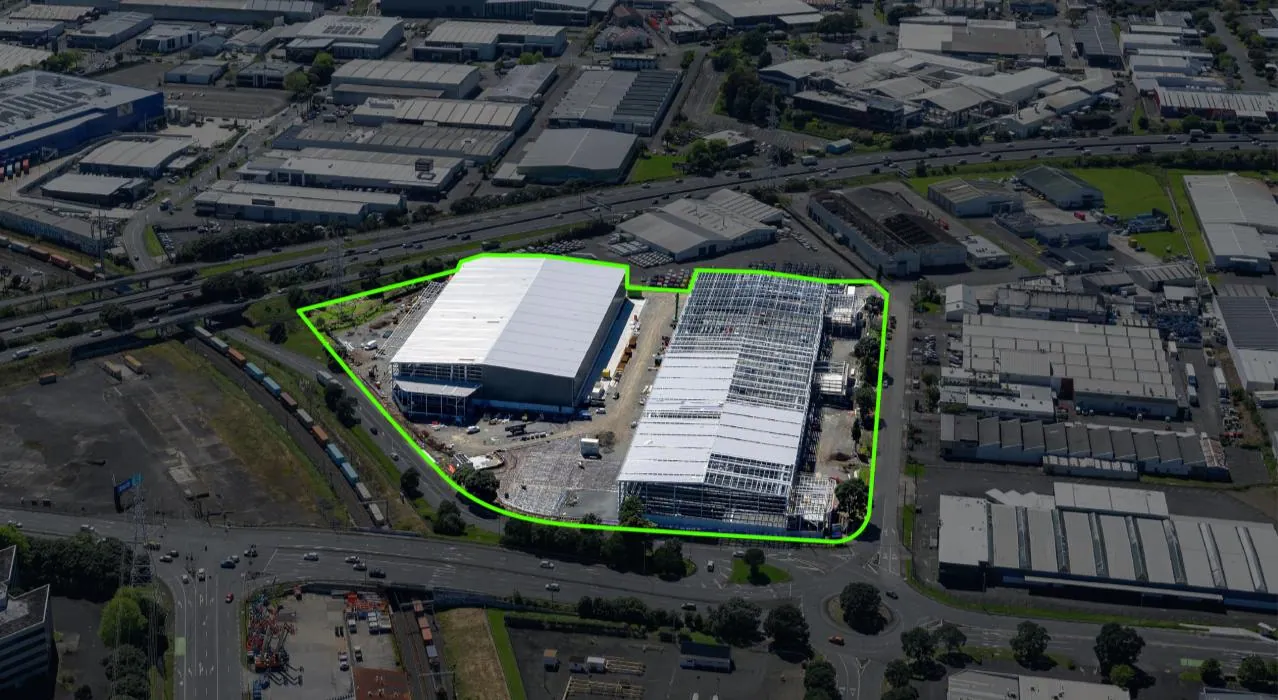
Goodman NZ is advancing several Auckland projects, including the more than NZ$1 billion development pipeline highlighted in its FY26 development pipeline. Mt Wellington Stage One was 42% leased, with commercial terms agreed for a further 26%, ahead of staged completion in the first quarter of 2027. The build-to-lease project is expected to provide about 21,850 square metres of warehouse space.
At Felix Street in Onehunga, demolition has finished and consenting is well progressed for a staged 27,520-square-metre warehouse development. At Waitomokia, negotiations are advanced for a first 3.3-hectare development pre-commitment with a large international customer, within an estate expected to support about 95,000 square metres of warehouse space.
Penrose data centre option absorbs further capital
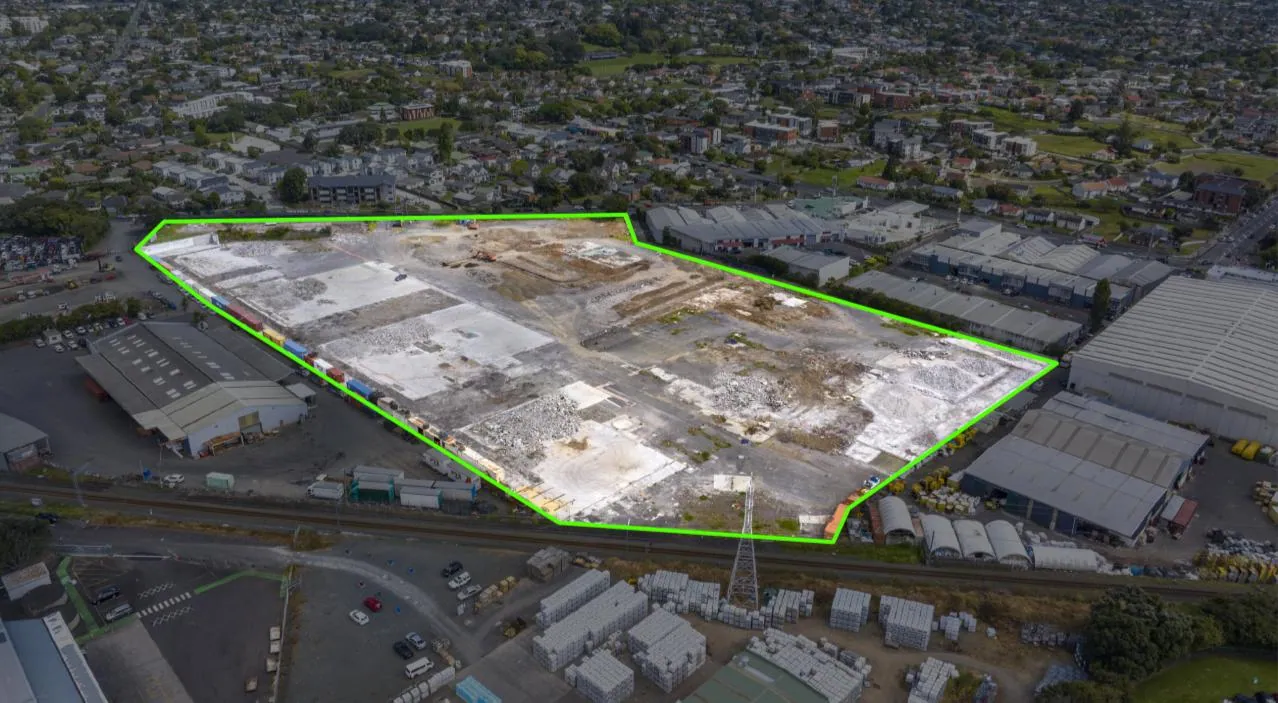
Penrose is the more speculative element of the programme. Goodman NZ has committed an additional NZ$10 million to detailed design and related workstreams for potential data centre use, while retaining flexibility over the site's eventual development. Demolition is complete, earthworks have begun and a works agreement for a 32MVA power connection keeps on-site power targeted for the first half of 2028.
The balance sheet gives the group room to pursue those projects. Look-through gearing was 22.2%, balance sheet gearing was 13.0%, and available liquidity was about NZ$464 million. Goodman NZ also bought back 18.14 million stapled shares at a weighted average NZ$1.95, which it said was a 7.9% discount to net tangible assets at 31 March 2026. Net tangible assets had risen to NZ$2.14 per stapled security by the half-year date.
Dividend holds while buyback continues
The interim dividend for Goodman New Zealand Limited was NZ$0.017925 per quoted equity security, with the full-year dividend guidance maintained at 7.17 cents per stapled security, representing a stated 5% increase on FY26. The first-half dividend represented 85.6% of Cash Earnings, according to the results presentation.
Goodman NZ intends to continue its on-market buyback while also assessing development and investment opportunities. The tension for the next six months is straightforward: leasing gains and rent reversion provide support, but the group must convert that potential while funding Mt Wellington, Waitomokia and the Penrose option without eroding the balance-sheet flexibility that currently distinguishes the result.
Get NZX:GNZ news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The guidance upgrade rests on recurring leasing strength, but delivery will depend on converting rent reversion and development commitments into cash earnings while the Highbrook accounting shift keeps reported revenue noisy.
Questions in the middle?
- How much of the 19.2% potential rent reversion can Goodman NZ convert as customer decisions remain slow?
- Will Mt Wellington and Waitomokia generate the expected leasing and pre-commitment momentum before further capital is deployed?
- Can the Penrose data centre option progress without narrowing the balance-sheet flexibility supporting the buyback and wider pipeline?
Sources
3-
Leasing activity underpins solid first-half result (opens in a new tab)Official market announcement. Goodman NZ Ltd & Goodman Property Services Ltd (NS) · 23 Nov 2026 · nz.goodman.com
-
Goodman NZ FY27 Interim Result Presentation (opens in a new tab)Official market announcement. Goodman NZ Ltd & Goodman Property Services Ltd (NS) · 23 Nov 2026 · nz.goodman.com
-
NZX Results Announcement Form (opens in a new tab)Official market announcement. Goodman NZ Ltd & Goodman Property Services Ltd (NS) · 23 Nov 2026 · nz.goodman.com