McLaren Minerals sets out a bigger path for titanium and zircon growth

McLaren Minerals has launched a discounted 8-for-5 entitlement offer seeking up to A$4.04 million to fund engineering, approvals, drilling and feasibility work across its mineral sands portfolio. The raise could more than double the company’s share count if fully subscribed, while only A$1 million is currently underwritten.
- 8-for-5 renounceable entitlement offer at A$0.005 per share
- Up to A$4.04 million proposed raise, with A$1 million partially underwritten
- Funds directed towards McLaren BFS work, approvals and Barossa exploration
- 529Mt McLaren resource at 4.5% heavy mineral
- Proposed loyalty options add a further potential security overhang
 Add us as a preferred source on Google
A$4.04 Million Raise Comes With Heavy Discount
McLaren Minerals Limited (ASX:MML) is asking shareholders for up to A$4.04 million at A$0.005 a share, a 54.5% discount to its 18 November closing price of A$0.011. The 8-for-5 renounceable entitlement offer would issue approximately 808.7 million new shares, potentially lifting the ordinary share count from 505.4 million to roughly 1.31 billion before accounting for any further securities.
The capital raising is only partially underwritten, to A$1 million by Leeuwin Wealth and subject to an underwriting agreement being executed before the prospectus is lodged. That distinction matters: the company has outlined a fully subscribed funding case, but its disclosed minimum funding scenario is considerably smaller.
Funding McLaren’s BFS and Barossa Drilling
McLaren says the money will support engineering and infrastructure, environmental studies, mining studies, water-bore testing and metallurgical work at its Western Australian titanium project. In the fully subscribed case, A$1.35 million is allocated to engineering, design and infrastructure, while A$800,000 is earmarked for environmental studies and approvals.
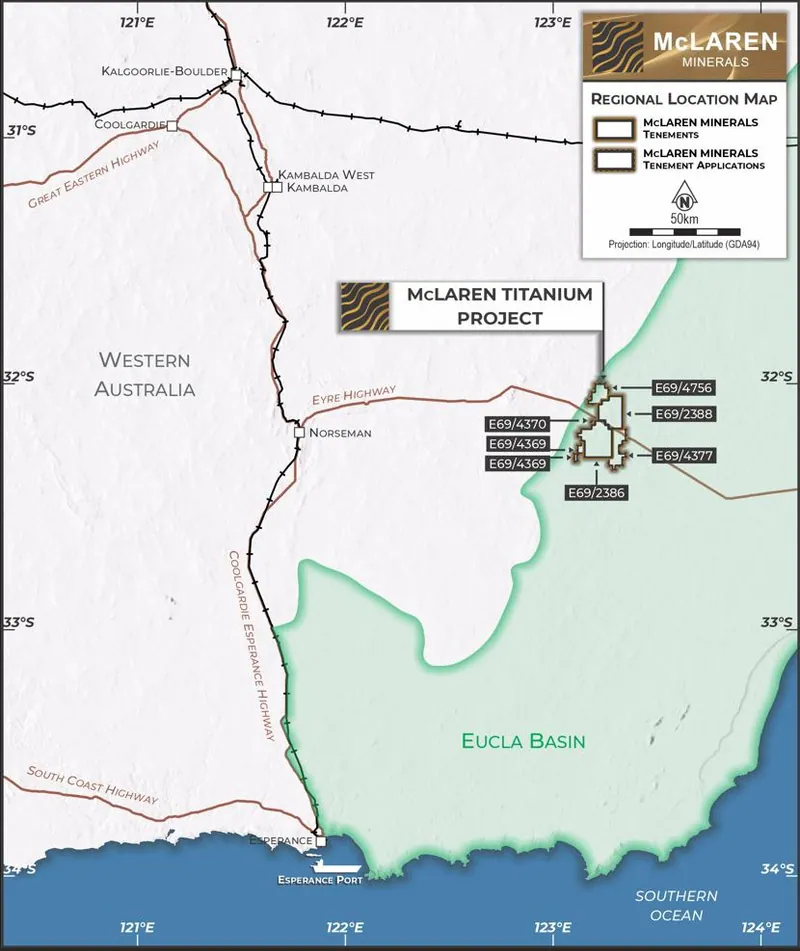
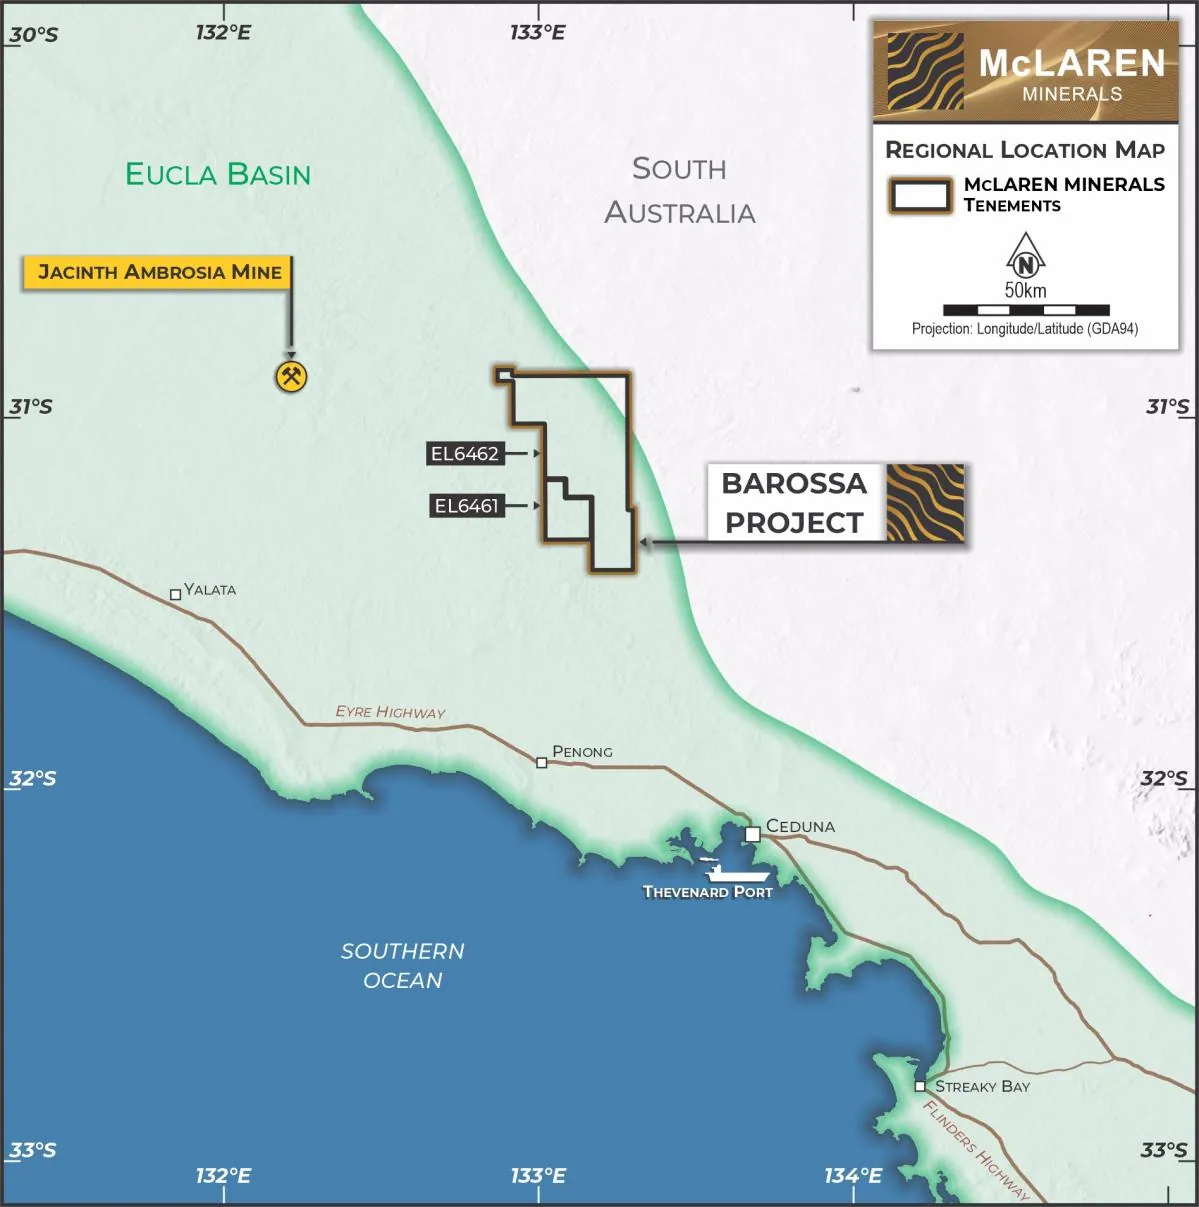
The balance is intended to move the Barossa project in South Australia from an exploration concept towards more defined drilling and mining studies. Barossa contains three prospects, an average reported heavy mineral grade of 4.6%, approximately 16% zircon in its assemblage and monazite presence. The company has flagged exploration as a key catalyst, but the project’s transaction and development pathway remain subject to further work and funding.
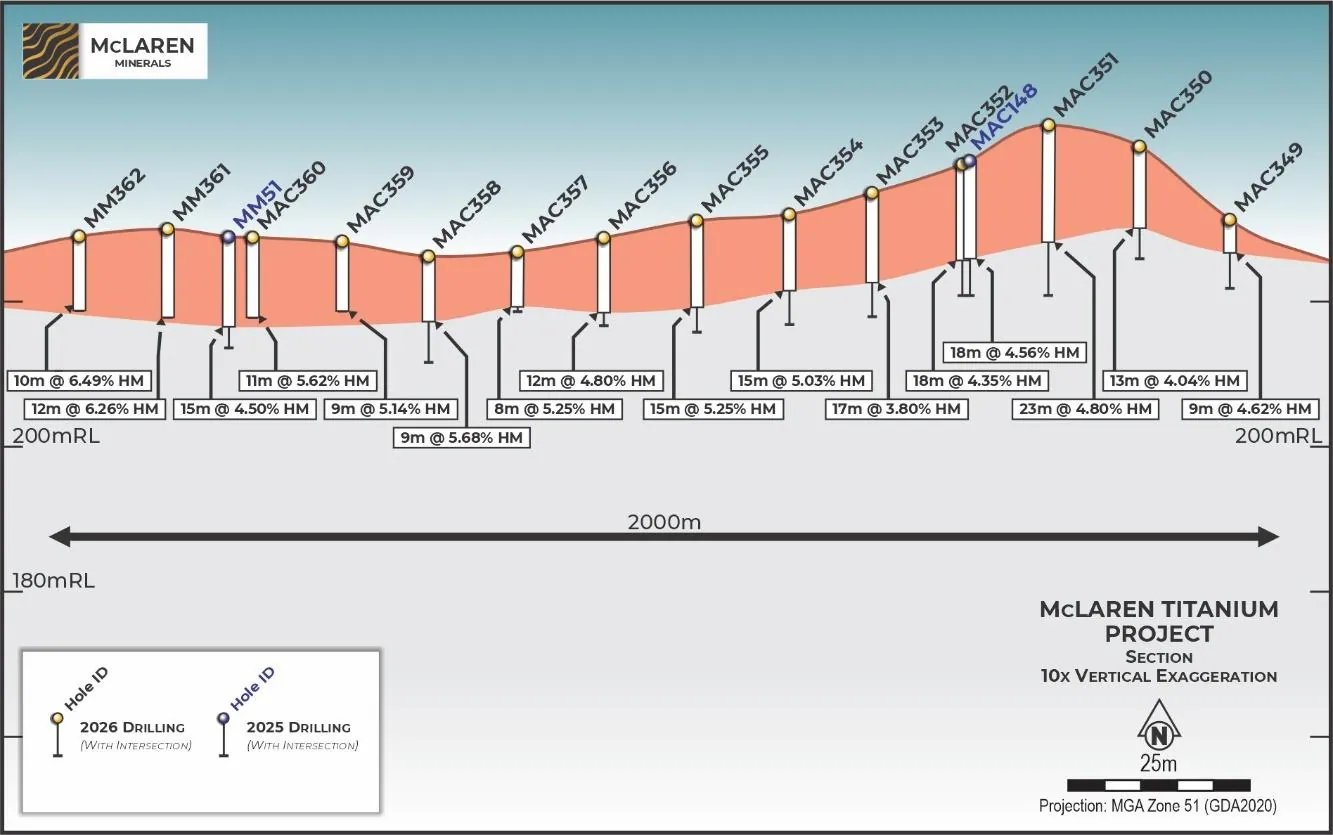
The funding need is not unexpected. McLaren had already completed its 663-hole, 11,568-metre drilling programme, and its recent McLaren BFS transition moved the flagship project into bankable feasibility work while highlighting the company’s reliance on additional capital. The presentation lists an indicative A$1.15 million cash balance at 30 September, making the proposed raise central to maintaining activity across both projects.
Large Resource, Attractive PFS Economics
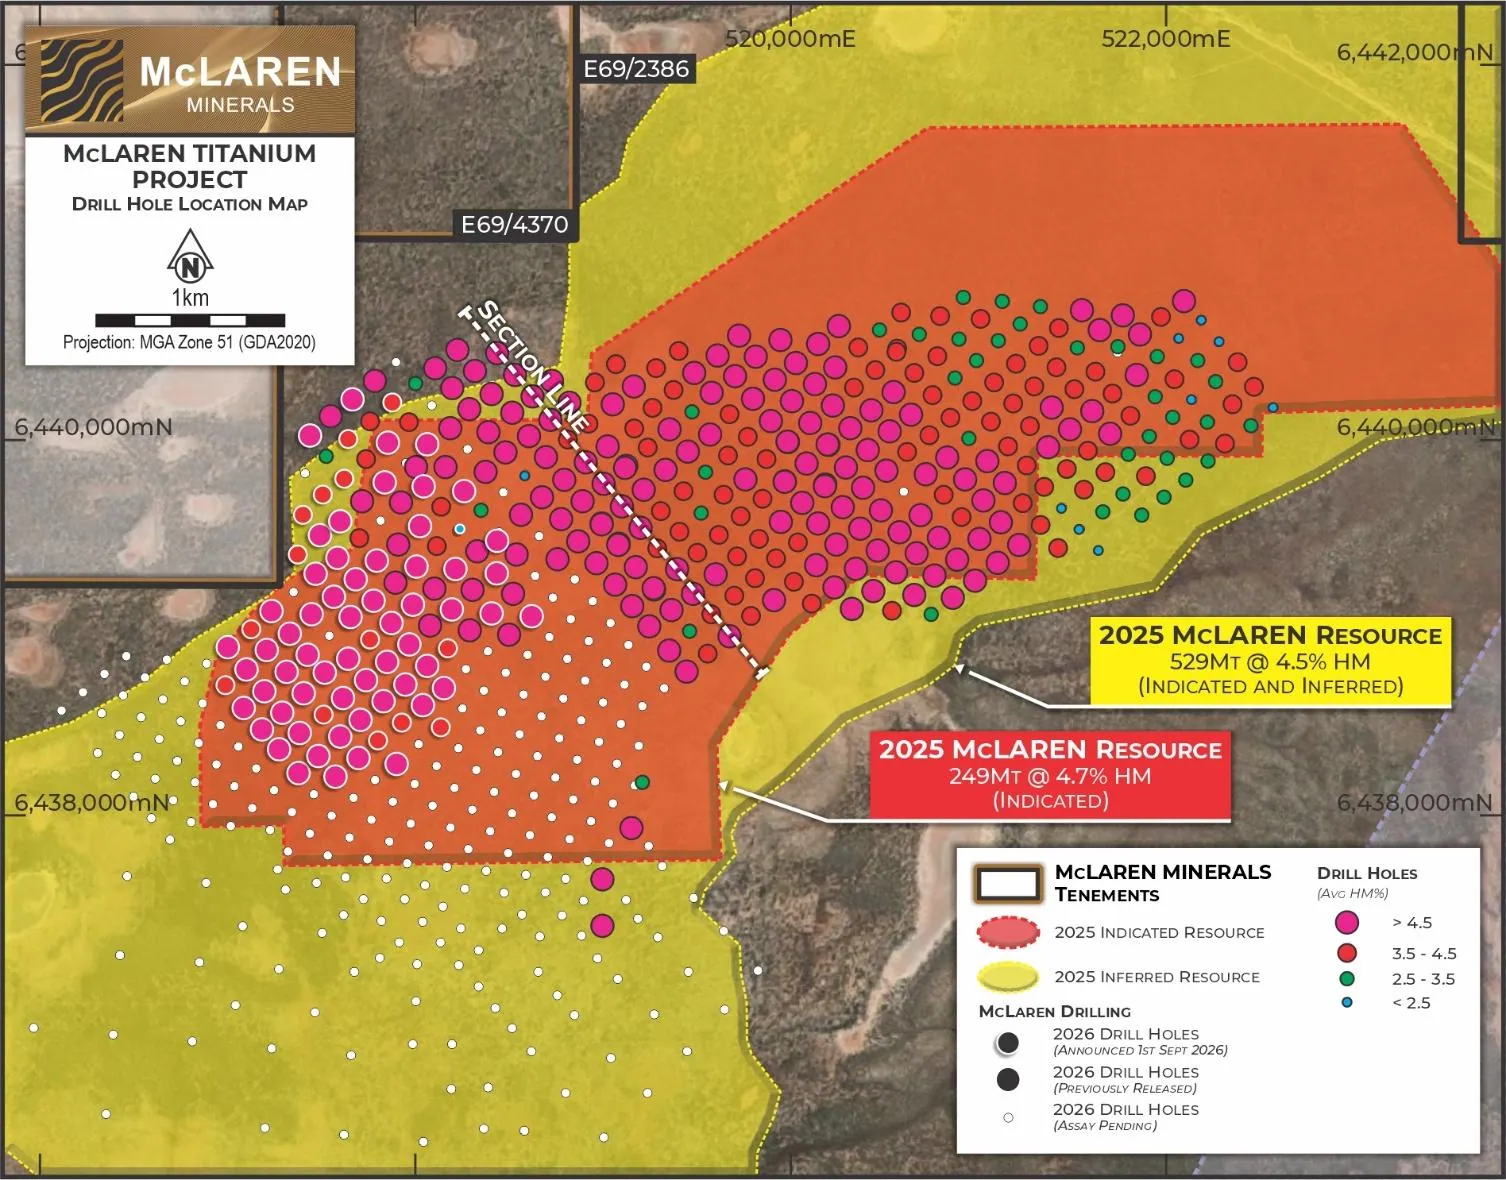
McLaren’s investment case rests on a 529 million tonne JORC Mineral Resource grading 4.5% heavy mineral, including 249 million tonnes in the Indicated category. The company says the resource contains approximately 6.96 million tonnes of in-situ ilmenite, alongside smaller quantities of rutile, leucoxene and zircon.
Its completed pre-feasibility study outlines a 15.9-year mine life, an average production rate of about 407,000 tonnes of ilmenite a year and pre-tax NPV8 of A$252 million. The study also reports a 26% internal rate of return, a 3.7-year payback and pre-production capital expenditure of A$179 million. Those figures are study estimates rather than an operating result, and the company is now using the BFS to test potential changes to throughput, mine life and project design.
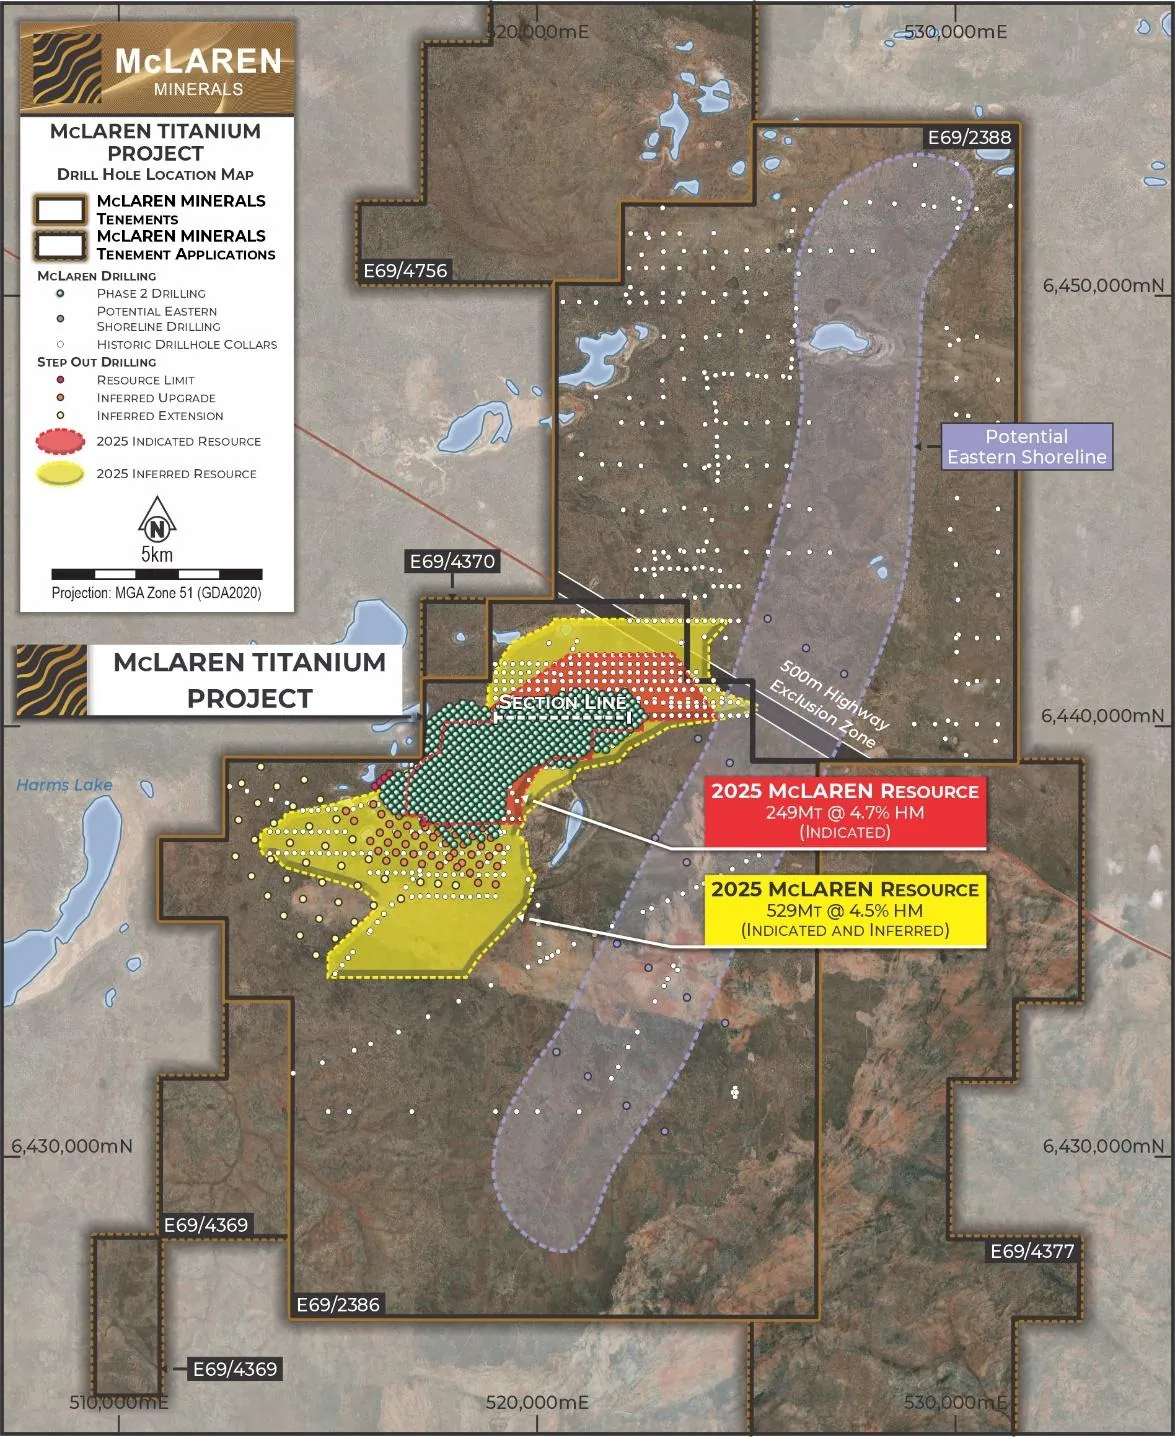
McLaren says the PFS mine plan covers only about 185 million tonnes of the 529 million tonne resource, leaving substantial material outside the current development case. That may provide optionality, but it also means the eventual scale and economics remain dependent on further technical work, approvals, funding and market conditions.
Shareholder Dilution and the Next Tests
Eligible shareholders in Australia and New Zealand are being offered the right to subscribe on an 8-for-5 basis, with the offer expected to open on 2 December and close on 16 December 2026. A separate proposed loyalty-option offer would provide one option for every three shares held on a future record date, with a proposed A$0.011 exercise price and February 2030 expiry. That proposal is not part of the current share issue and remains subject to a separate prospectus.
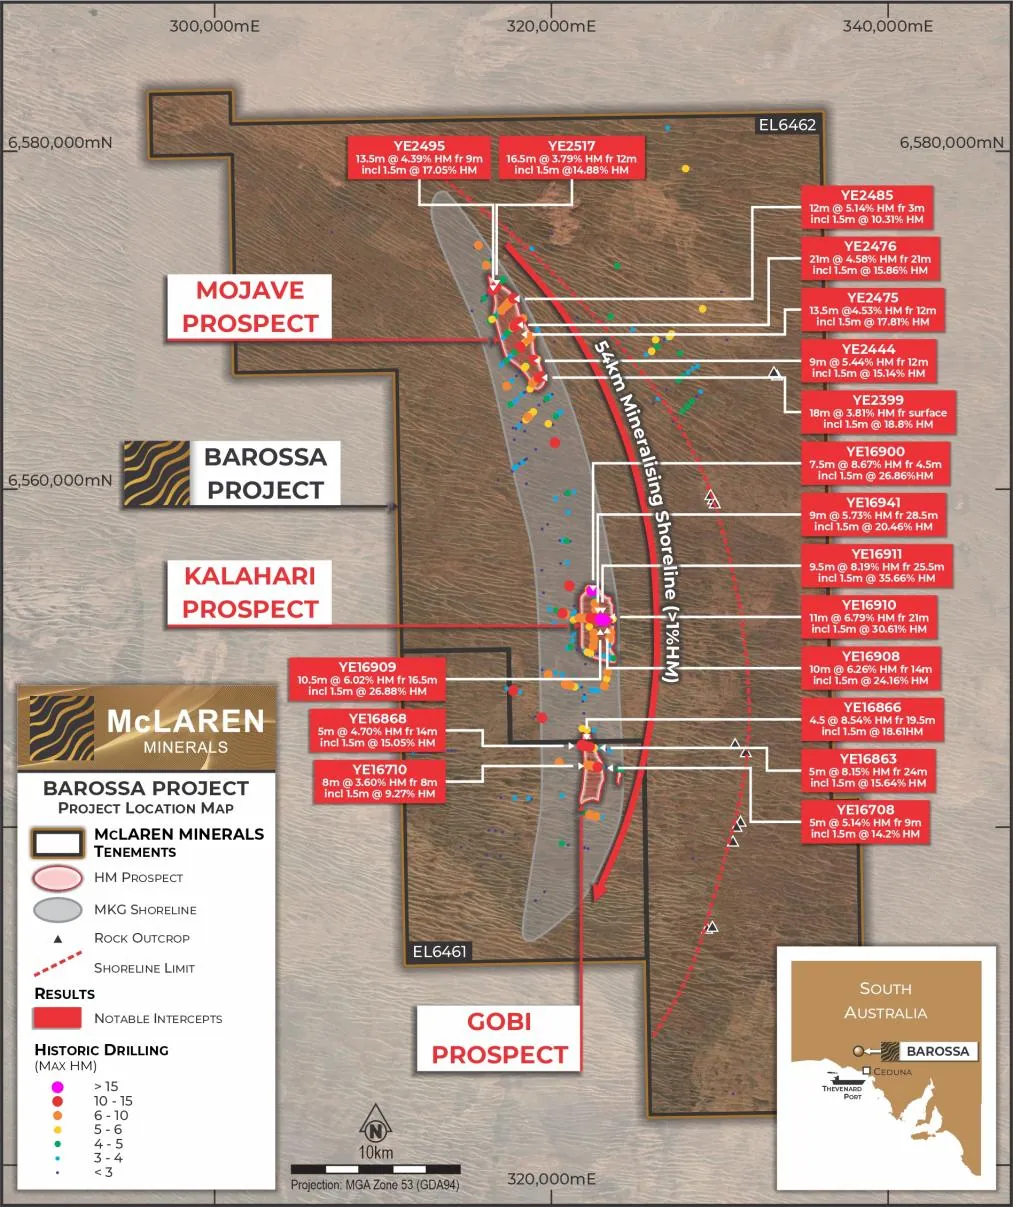
The immediate question is how much of the offer shareholders take up, and whether the company can secure the full funding envelope rather than the A$1 million currently underwritten. The next substantive milestones are the BFS work, an updated McLaren resource estimate incorporating 2026 drilling, potential Barossa transaction completion and the first phase of Barossa exploration. Until those steps produce firmer development and financing evidence, the project’s sizeable PFS value sits alongside a very small market capitalisation and a material capital requirement.
Get ASX:MML news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
McLaren has a large resource and an encouraging PFS, but the offer’s limited underwriting means funding certainty remains the near-term test.
Questions in the middle?
- How much of the A$4.04 million target will shareholders ultimately fund?
- Will the BFS preserve the PFS economics while expanding the mine plan or throughput?
- Can Barossa’s zircon and monazite potential justify allocating scarce capital alongside McLaren?
Sources
1-
Investor Presentation (opens in a new tab)Verified source. McLaren Minerals Limited · 23 Nov 2026