Moab’s Manyoni expansion faces dilution and funding pressure

Moab Minerals has secured four additional prospecting licences around its Manyoni uranium project in Tanzania, but ended September with just A$21,000 in cash. Planned testwork and 2027 drilling now depend on a conditional A$350,000 loan, further fundraising and creditor support.
- Four AuKing prospecting licences transferred to Moab
- 62.5 million consideration shares require shareholder approval
- Manyoni resource remains 27.19 million pounds of U3O8
- A$21,000 cash at 30 September and 0.17 quarters of funding
- A$350,000 convertible loan conditional on approval and a future capital raising
 Add us as a preferred source on Google
Manyoni Expansion Meets Severe Liquidity Constraint
Moab Minerals Limited (ASX:MOM) has added four prospecting licences to its Manyoni Uranium Project in Tanzania, extending the company’s ground position over interpreted uranium-bearing palaeochannels. The strategic expansion is paired with a much more immediate financial problem: Moab held only A$21,000 in cash at 30 September and calculated its available funding at just 0.17 quarters.
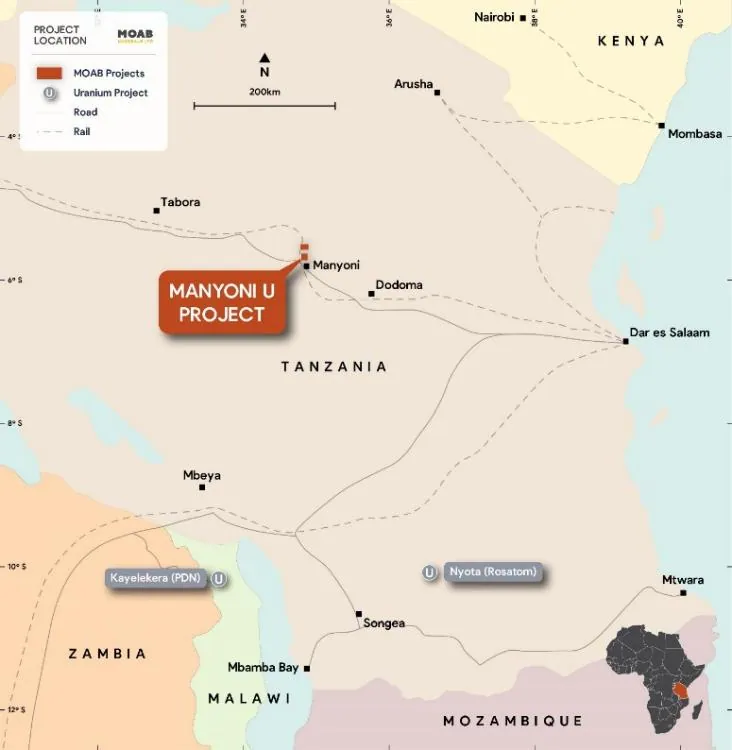
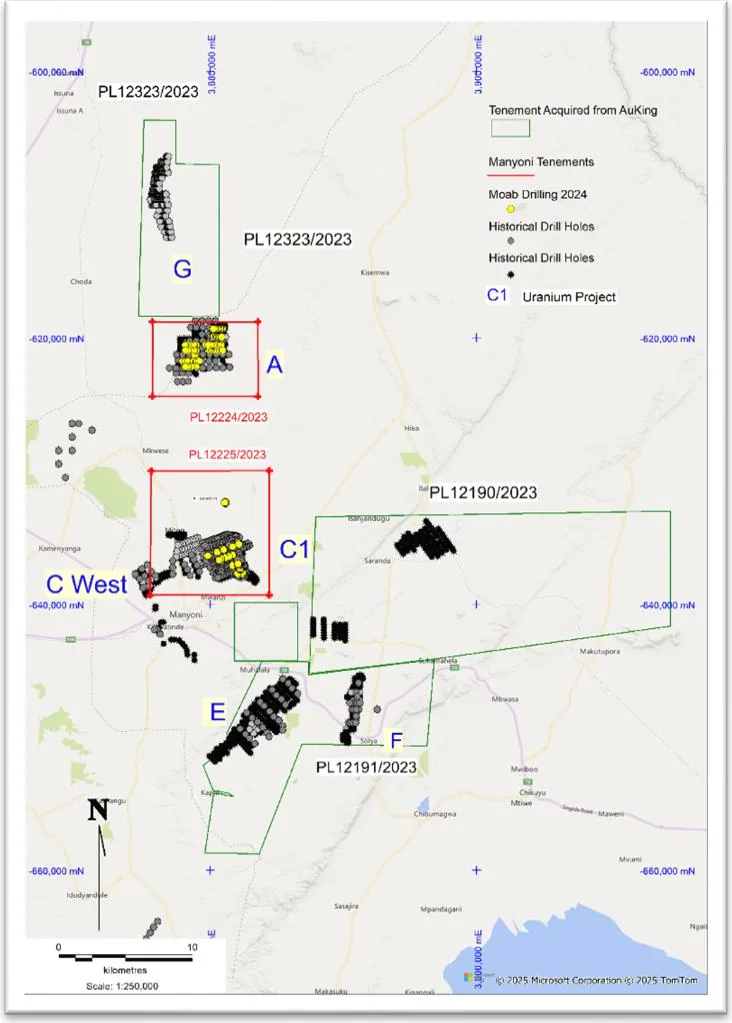
The licences, transferred from AuKing Ltd (ASX:AKN), cover a combined 488.5 square kilometres and sit adjacent to Moab’s existing Manyoni tenements. The consideration is 62.5 million fully paid shares, which still require shareholder approval at the annual general meeting scheduled for 30 November. Those shares would be subject to a six-month voluntary escrow from issue.
The transaction builds on Moab’s Manyoni focus without requiring a cash payment in the quarter. The project’s current JORC 2012 Mineral Resource Estimate contains 27.19 million pounds of U3O8 at an average grade of 136 parts per million, based on a 100 parts per million cut-off and representing a 25% increase over the previous estimate. Historical estimates associated with some of the newly transferred prospects predate JORC 2012 and are not presented as current compliant resources.
Testwork and Drilling Remain Funding Dependent
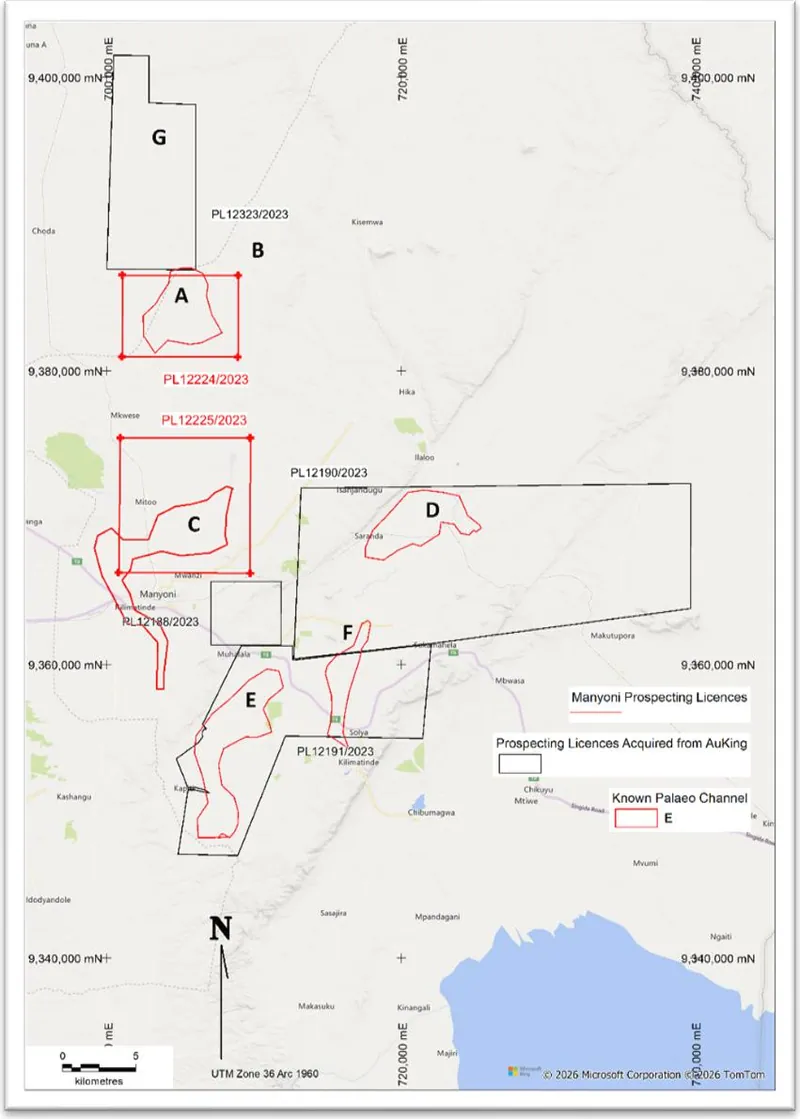
Moab says historical drilling across the acquired licences targeted palaeochannels forming part of a broader northwest-trending palaeodrainage system. The company believes validation and step-out drilling could investigate extensions of known mineralisation and potentially support additional resources, but those possibilities remain untested by the current programme.
The proposed next stage is preliminary mineralogical and metallurgical work, including physical characterisation and uranium leach testing. Results could inform further technical studies, including a potential scoping study. Drilling is currently contemplated for calendar 2027, subject to funding and regulatory approvals. No exploration work was carried out at the Highline Copper-Cobalt Project in Nevada during the quarter.
Conditional Loan Adds Cash but Raises Dilution Questions
After quarter-end, Moab entered into a binding unsecured convertible loan agreement for A$350,000 at 8% annual interest. Subject to shareholder approval, the lender may convert at a 50% discount to the issue price of Moab’s next placement or rights issue, with a minimum conversion price of A$0.0005 a share. If approval is not obtained within six months, the loan and accrued interest are repayable in cash.
The agreement is also conditional on Moab completing a placement or rights issue and holding at least A$1 million in cash after that raising. The company said it continues to consider equity funding, liability-to-equity conversions and other financing options, while some creditors have agreed to defer payment and exploration spending can be deferred. Moab’s existing drawn loan facilities totalled A$1.8 million at quarter-end, including A$1.3 million owed to European Lithium Ltd (ASX:EUR) and A$500,000 owed to Goldshore Investments.
September Spending Leaves Little Room for Delay
Quarterly cash outflows included A$59,000 in administration and corporate costs, A$20,000 in staff costs, A$47,000 in exploration and evaluation expenditure and A$32,000 in acquisition due diligence. The company recorded net cash used of A$79,000 in operating activities and A$79,000 in investing activities, partly offset by A$10,000 in borrowings and a A$3,000 foreign exchange movement.
The central question is no longer whether Manyoni offers a larger exploration footprint. It is whether Moab can fund the technical work needed to test that opportunity before its existing liquidity and creditor arrangements become binding constraints. The November shareholder vote, the structure of any capital raising and the terms attached to any resulting dilution will determine how much of the proposed 2027 programme can move beyond the planning stage.
Bottom Line?
Manyoni now has more exploration ground, but the project’s next meaningful test depends on Moab securing capital well before its 0.17-quarter cash runway expires.
Questions in the middle?
- Will shareholders approve the 62.5 million consideration shares and the A$350,000 convertible loan?
- Can Moab complete a placement or rights issue that satisfies the loan’s A$1 million post-raising cash condition?
- Will metallurgical work and validation drilling produce enough evidence to justify advancing Manyoni toward a scoping study?
Sources
1-
Quarterly Activities Report and Appendix 5B (opens in a new tab)Official market announcement. Moab Minerals Limited · 27 Oct 2026 · moabminerals.com.au