Rumble reveals stronger Western Queen economics with tungsten upside ahead

Rumble Resources has outlined a preliminary A$86 million pre-tax NPV for Western Queen, with a 45% IRR and almost four years of planned underground production. The study also leaves room for tungsten upside, but financing, approvals and a feasibility study remain unresolved.
- A$86 million pre-tax NPV at an 8% discount rate
- 1.2Mt production target containing 125,000oz of gold
- A$133 million pre-tax free cash flow and 45% IRR
- A$4,390/oz all-in sustaining cost at an assumed A$5,714/oz gold price
- Tungsten excluded from the base-case economics pending further study
 Add us as a preferred source on Google
Western Queen economics improve on a larger underground plan
Rumble Resources Limited (ASX:RTR) has put an A$86 million headline value on its Western Queen gold project, with an updated scoping study pointing to A$133 million in pre-tax free cash flow and a 45% internal rate of return. The proposed operation would mine 1.2 million tonnes at 3.2 grams per tonne for 125,000 ounces of contained gold, using underground stoping at Western Queen South and Western Queen Central.
The plan is materially larger than the November 2025 Western Queen South study, according to Rumble, with the updated mine schedule extending the initial production period to almost four years. At full production, the operation is expected to process about 30,000 tonnes of mineralised material a month, with first milling of Western Queen ore targeted for the second quarter of 2028.
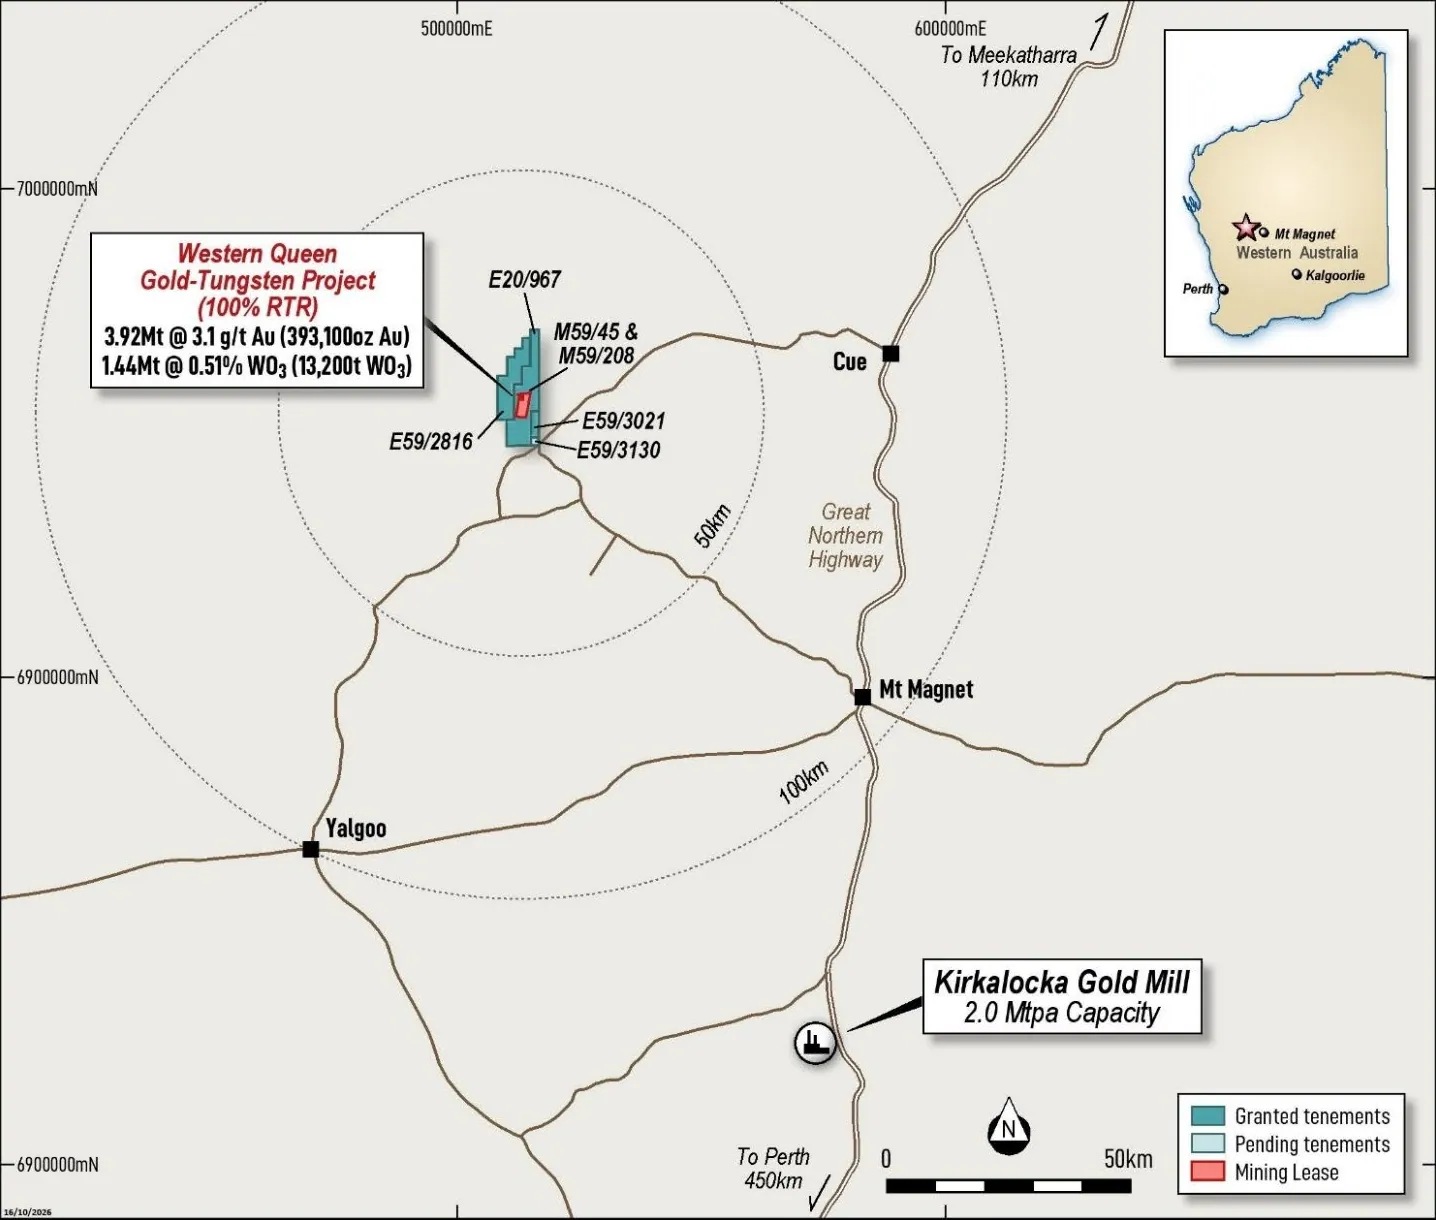
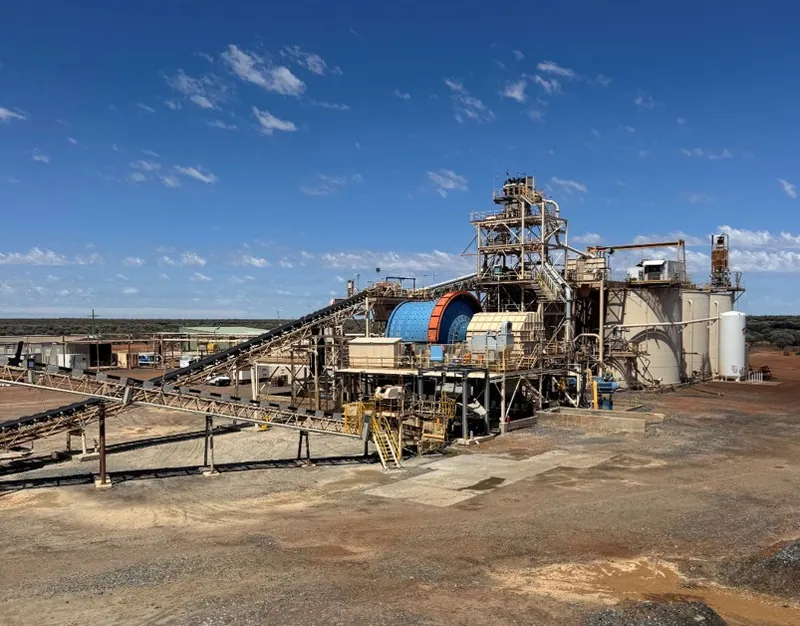
The project’s development pathway has already moved beyond a purely conceptual processing plan. Rumble has a five-year toll milling and blending agreement with Gylden Resources and Kirkalocka Gold SPV, under which ore would be trucked about 185 kilometres southeast to the Kirkalocka plant. The plant is being refurbished and is expected to come online in early 2027. The agreement gives Rumble access to conventional crushing, grinding, gravity and leaching infrastructure without requiring a processing plant at Western Queen.
That pathway builds on the Western Queen financing pathway, which had identified third-party processing access and royalty funding but also left the project dependent on further approvals, financing and a final investment decision.
Higher-grade resource reshapes the mine plan
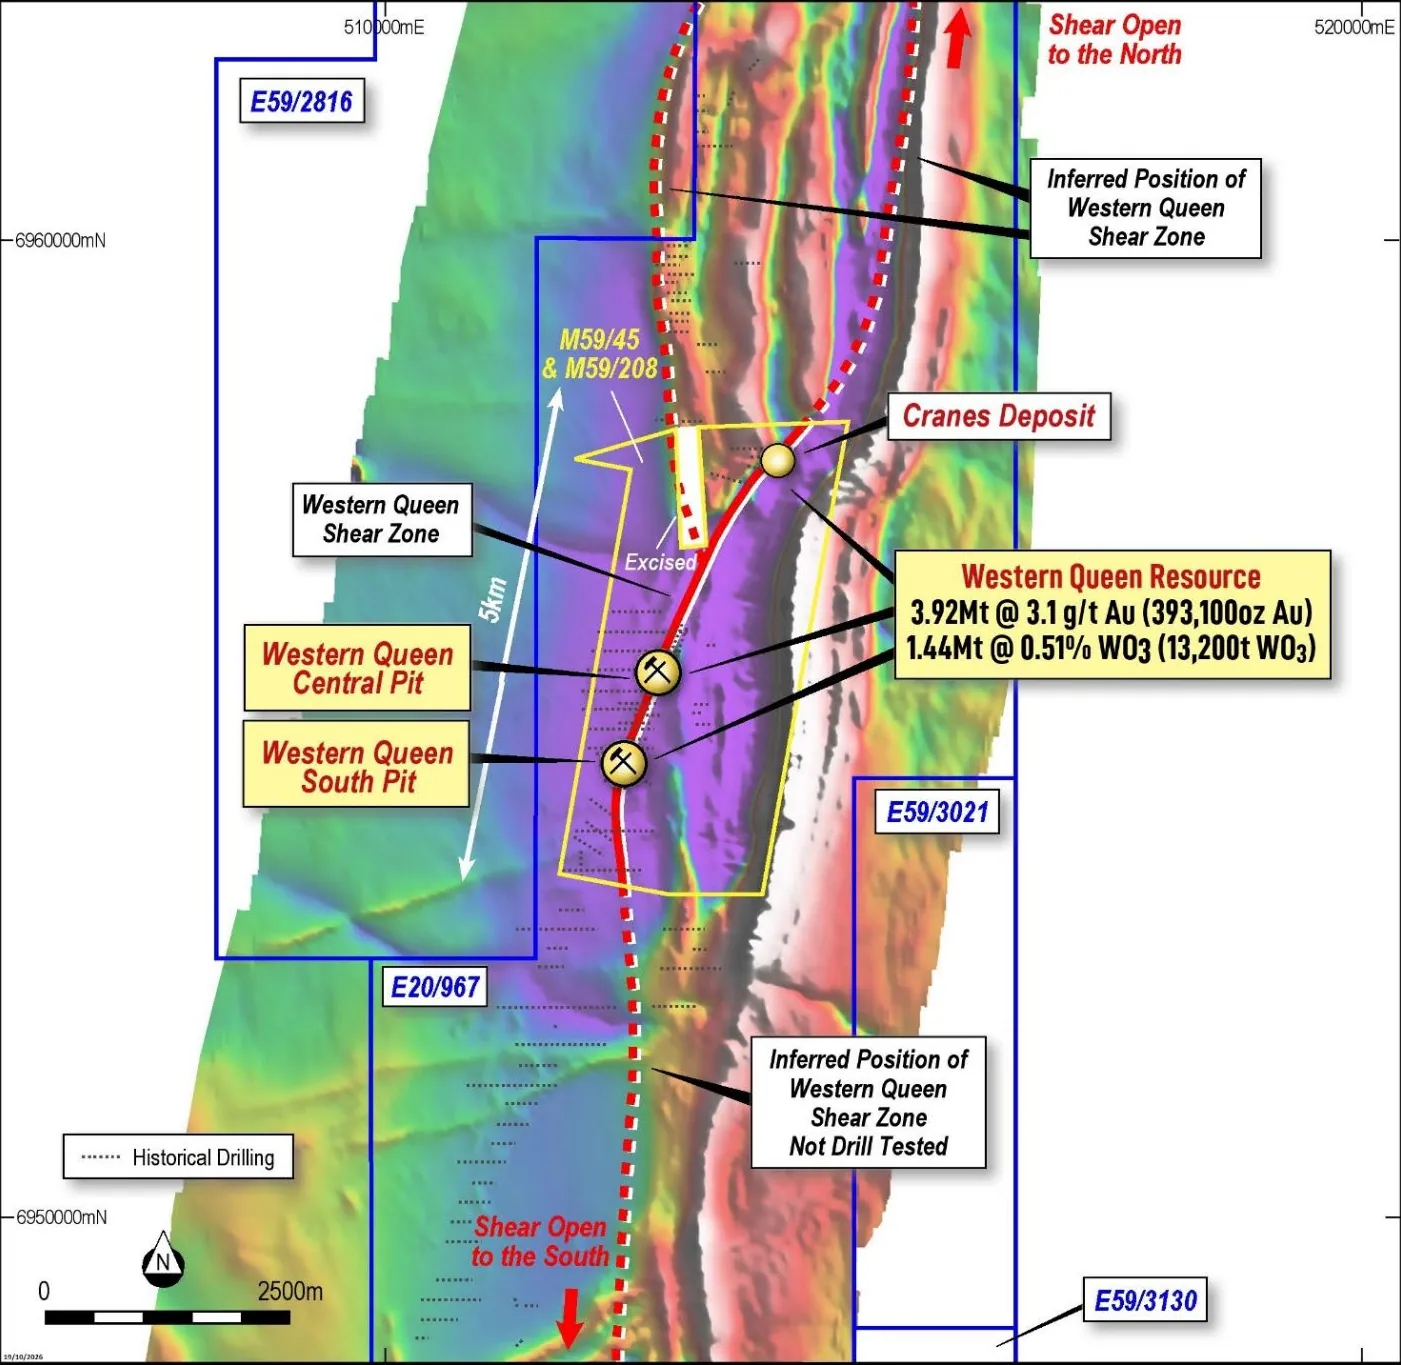
The study uses a revised resource of 3.92 million tonnes at 3.1 grams per tonne for 393,100 ounces of gold, including 1.87 million tonnes at 3.7 grams per tonne for 223,800 ounces in the Indicated category. Rumble says the underground-focused model lifted the overall resource grade by 19% compared with its June estimate, while Indicated grades at Western Queen South and Central rose 27% with only a negligible reduction in contained ounces.
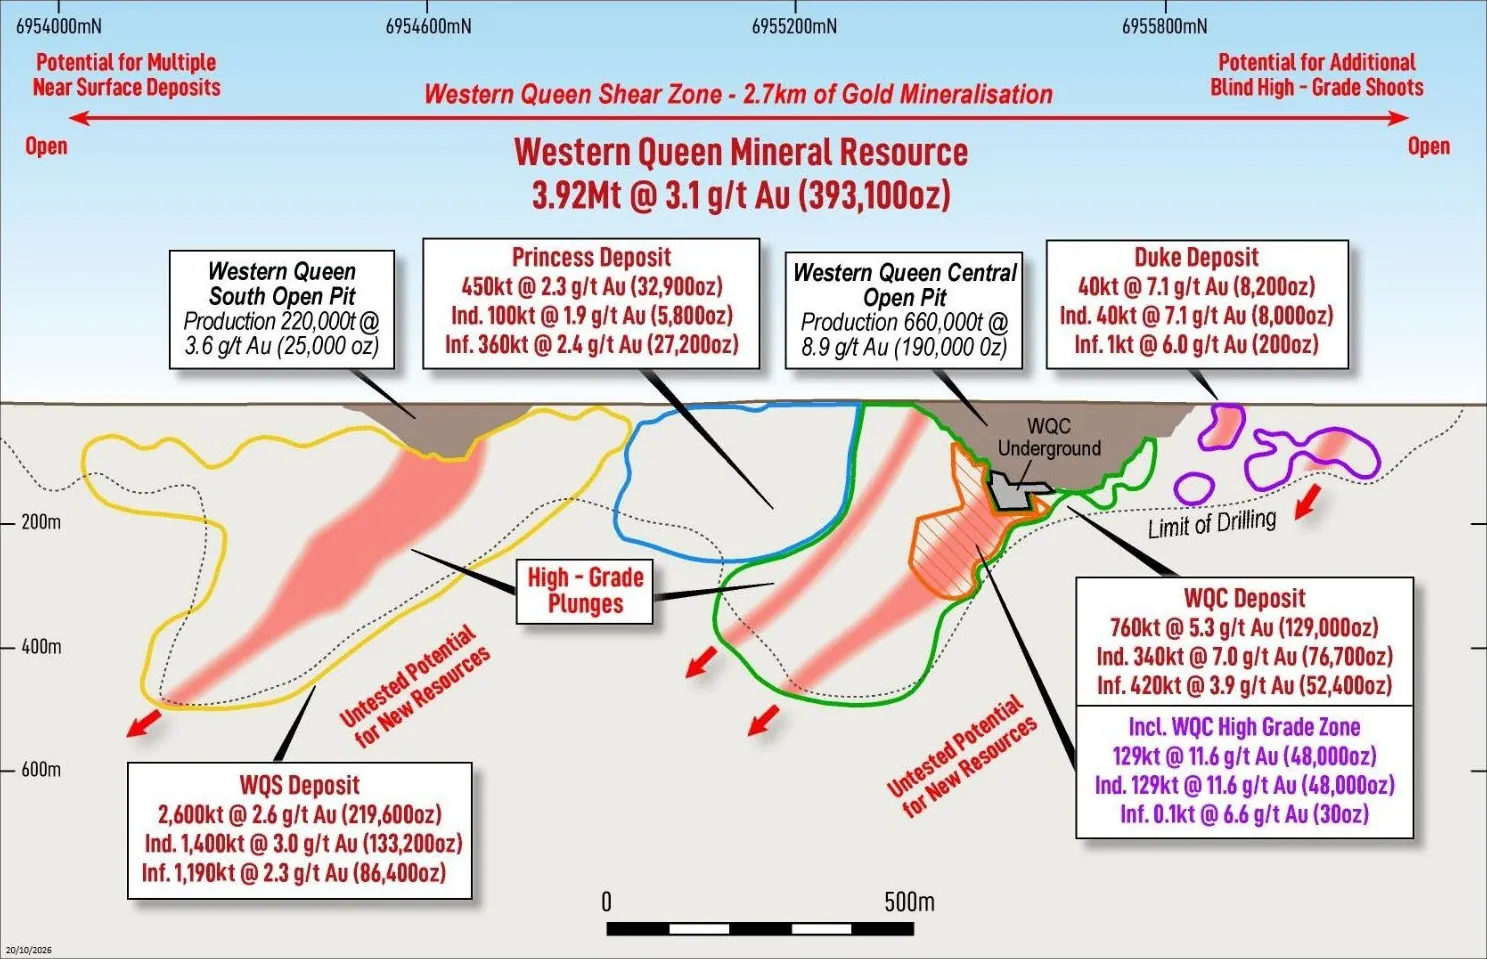
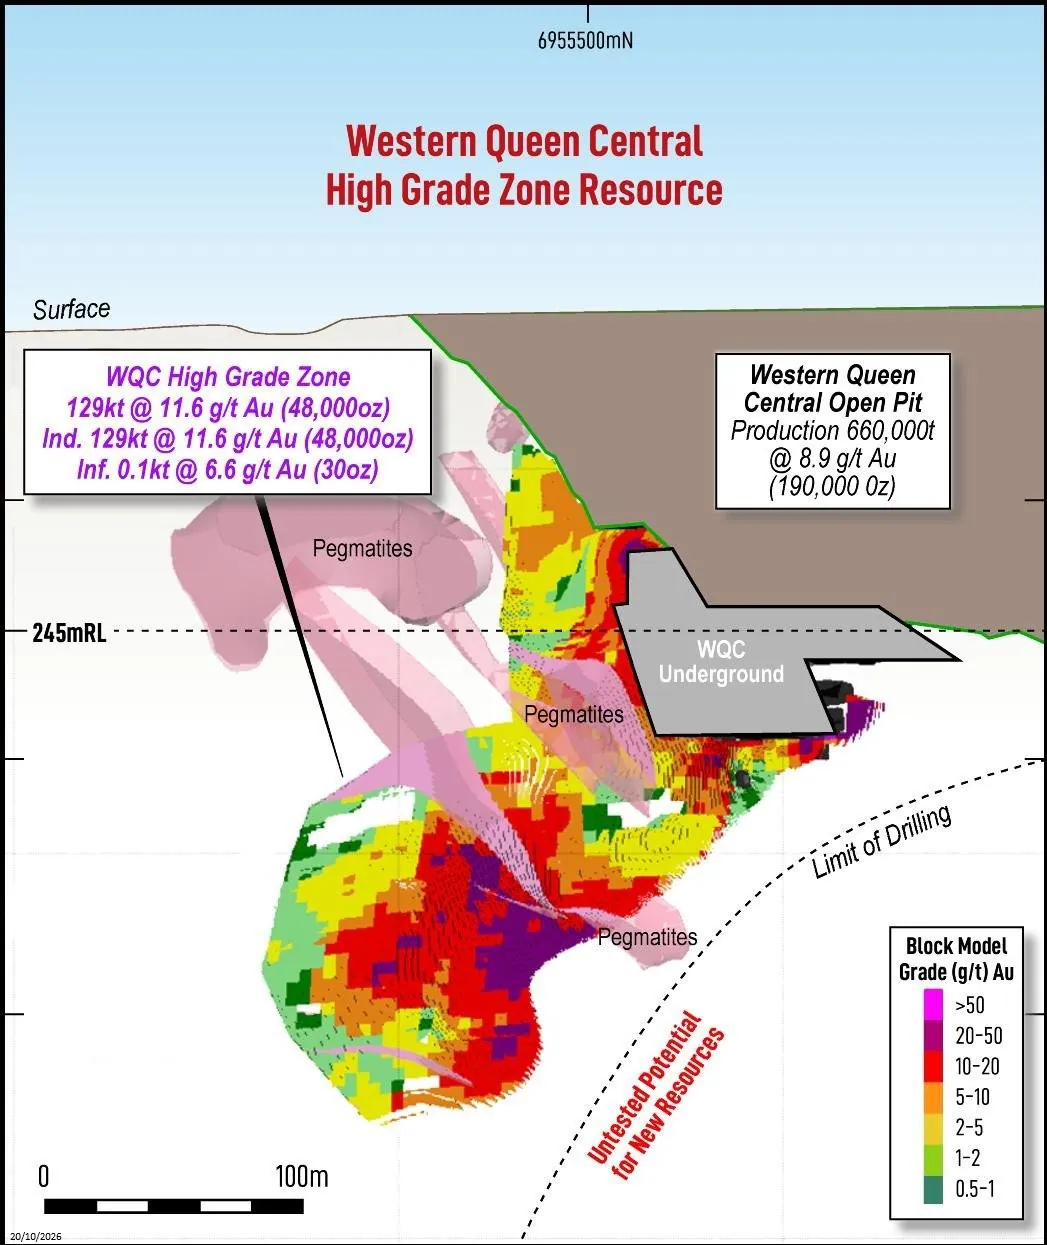
A particularly important component is a 129,000-tonne high-grade zone at Western Queen Central grading 11.6 grams per tonne for about 48,000 ounces. The zone sits beneath historical underground workings and has been incorporated into the proposed mine design, helping give the updated study a more selective underground focus.
However, the study’s production target is not an Ore Reserve. It comprises 80% Indicated and 20% Inferred material by mass, and Rumble cautions that the Inferred component carries lower geological confidence. The company says only about 30% of the current mineral resource is included in the production target, leaving potential mine-life extension, but that potential still depends on further drilling, resource conversion and technical work.
Tungsten could add value, but is absent from the base case
The most intriguing omission from the headline economics is tungsten. Rumble says tungsten is co-mingled with the gold mineralisation and has identified a resource of 4.31 million tonnes at 0.31% tungsten trioxide, containing 13,200 tonnes of tungsten trioxide. Initial testwork and preliminary marketing discussions indicate that a saleable scheelite concentrate may be possible.
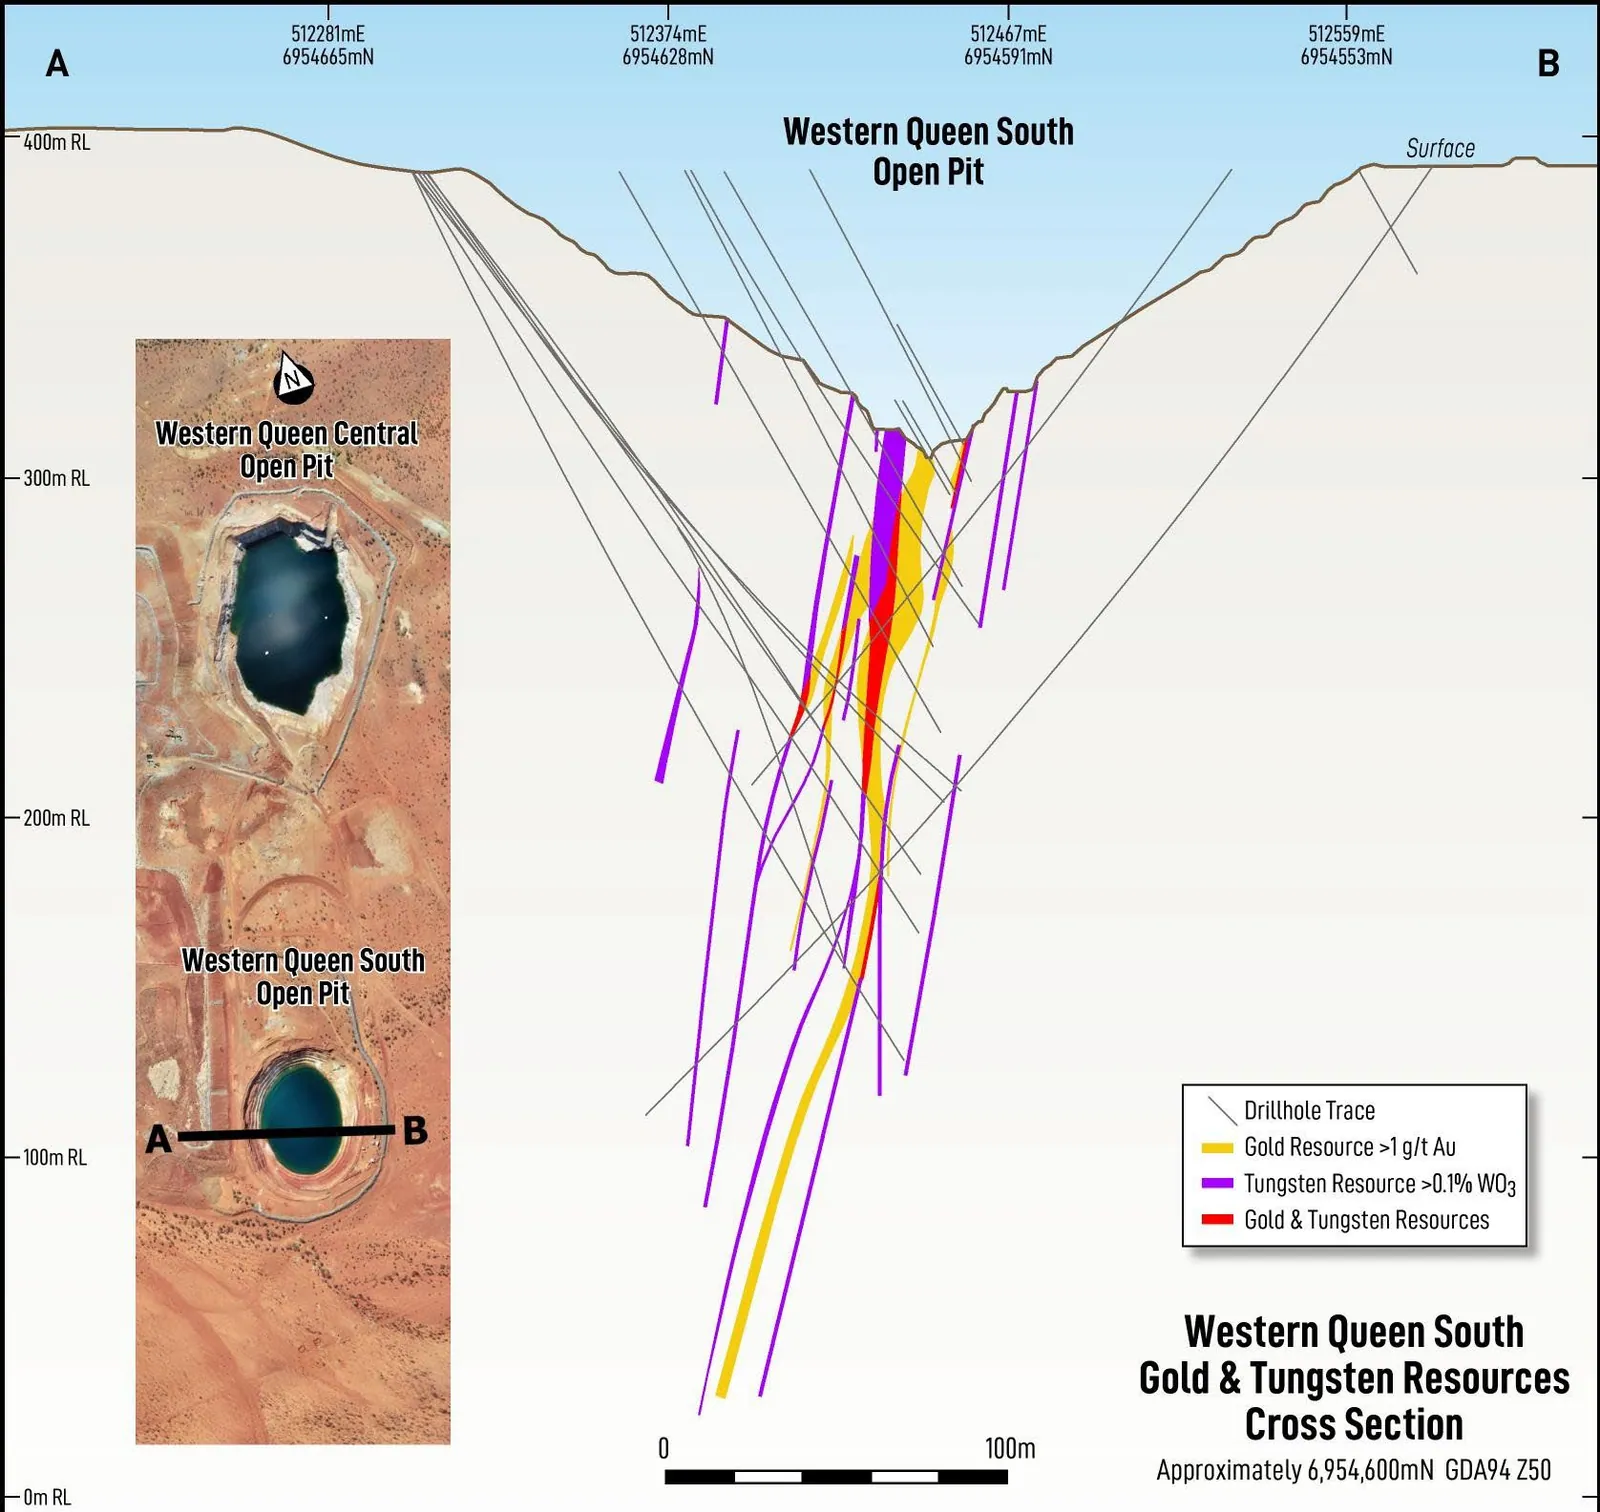
That potential revenue stream is not included in the A$86 million NPV or A$133 million free cash flow figures. Rumble and Gylden are instead reviewing a possible tungsten circuit at Kirkalocka, with a detailed engineering study expected to examine the required plant modifications, recoveries and capital costs. The next feasibility study is intended to incorporate the tungsten material into the mine plan.
Low initial capital does not remove the funding risk
Pre-development capital is estimated at about A$8 million, with total capital costs of A$95 million including underground development and infrastructure. The study assumes A$4,390 per ounce in all-in sustaining costs against a flat gold price of A$5,714 per ounce, with an 8% discount rate. Rumble notes that its assumed gold price is below the cited one-year Perth Mint average and close to the spot price at the time of the announcement, but the economics remain sensitive to the assumptions.
At a 20% reduction in the assumed gold price, modelled pre-tax free cash flow falls to A$8 million, compared with A$133 million in the base case. A 20% increase in mining costs reduces free cash flow to A$91 million, while a 20% increase in processing costs reduces it to A$112 million. The figures are indicative rather than precise forecasts: the scoping study carries an accuracy range of plus or minus 30%.
Rumble says it is discussing debt financing and other funding options, but has no funding commitments in place. The company acknowledges that any future funding may be dilutive or otherwise affect existing shareholders, while the project could also be subject to a sale, partial sale or joint venture.
Approvals and feasibility work set the next test
Most key permits for dewatering, mine development and production have been received, according to Rumble. The outstanding major approval is the Mine Development and Closure Proposal. Dewatering the flooded Western Queen South pit is expected to take about three months, while underground development is scheduled to begin in the second quarter of 2027 under the study assumptions.
The company’s October Western Queen development update had already identified the same approval, financing and study milestones as the key hurdles before a decision to mine. The updated study now puts numbers around the proposed operation, but it does not yet convert the resource into a reserve or establish that development will proceed.
The next meaningful markers are the feasibility study, blended-ore metallurgical work, tungsten recovery testing, the remaining approval and a financing package. The central question is whether the attractive scoping-study economics survive once those assumptions are replaced with firmer costs, recoveries, funding terms and a mineable reserve.
Get ASX:RTR news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The study gives Western Queen a stronger economic shape, but the investment case still hinges on converting a preliminary production target into a funded, permitted mine.
Questions in the middle?
- Can Rumble secure project funding without materially diluting existing shareholders?
- Will the feasibility study preserve the base-case economics after tungsten, blended-ore recovery and firmer cost estimates are included?
- How much of the Inferred resource can be converted into Indicated material and ultimately an Ore Reserve?
Sources
2-
Western Queen Scoping Study (opens in a new tab)Verified company source. Rumble Resources Limited · 28 Oct 2026 · investors.rumbleresources.com.au
-
Western Queen MRE Optimised for Underground Mining Study (opens in a new tab)Verified company source. Rumble Resources Limited · 28 Oct 2026 · investors.rumbleresources.com.au