Cue Energy’s cash engine strengthens as Mahato well beats expectations

Cue Energy Resources (ASX:CUE) increased quarterly cash receipts 29% to A$17.5 million and finished September with A$18.1 million in cash. Mahato’s PB-42 well exceeded pre-drill expectations, while Palm Valley’s PV14 entered production and PV15 drilling began, although total production fell from the previous quarter.
- Quarterly cash receipts rose to A$17.5 million and closing cash to A$18.1 million
- Mahato PB-42 began at 520 bopd gross, above pre-drill expectations
- Palm Valley PV14 is flowing at about 0.5 TJ/d and PV15 is drilling
- Sixth consecutive dividend paid, taking cumulative shareholder returns to A$35 million since 2024
- Total production declined to 121.5 kboe, while Sampang output continued to mature and decline
 Add us as a preferred source on Google
Cash generation strengthens despite lower production
Cue Energy Resources (ASX:CUE) has opened FY2027 with a sharper cash position, collecting A$17.5 million during the September quarter, up from A$13.6 million in the previous three months. Closing cash rose A$2.4 million to A$18.1 million, helped by higher realised oil prices and the timing of receipts.
The improvement came even as total production fell to 121.5 thousand barrels of oil equivalent from 138.1 kboe. Brent, which underpins Cue’s Mahato and Maari oil sales, averaged about US$96 a barrel during the quarter and about US$125 a barrel in the first three weeks of October, giving the company a favourable pricing backdrop but leaving cash generation exposed to commodity-market movements.
Mahato well beats expectations as approvals near
Mahato delivered the clearest operational signal. The PB-42 development well began producing at 520 barrels a day gross after being connected to the existing production system, exceeding pre-drill expectations. PB-41 and three workovers were also completed, while the next development phase targeting the Bekasap and Telisa reservoirs moved into the final stages of government approval.
Cue’s net Mahato production nevertheless dropped to 38,234 barrels from 53,849 barrels because of the production-sharing contract’s cost-recovery mechanism. Cash receipts moved in the opposite direction, rising 89% to A$10.2 million. Planning for the GA-1 exploration well is also progressing, although early-2027 drilling remains subject to land access and regulatory requirements. The field’s development program was identified as part of the near-term growth agenda in Cue’s FY2026 dividend update.
Palm Valley drilling supports contracted gas supply
At Palm Valley, PV14 was tied into the gathering system and began flowing on 23 October at approximately 0.5 terajoules a day. Cue said it plans to evaluate the well’s performance, including whether current flow rates are being influenced by wellbore conditions or reservoir pressure. PV15 is drilling ahead, with total depth expected around mid-December.
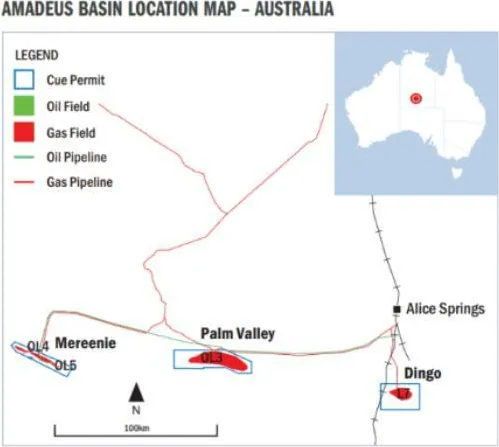
The two-well program supports long-term contracted gas supply to the Northern Territory Government through 2034. Mereenie and Dingo production remained broadly stable, while Palm Valley output averaged 5.6 TJ a day gross during the quarter. The drilling program follows the Palm Valley drilling plan, which was reported alongside Cue’s previous quarterly production increase.
Maari recovers while mature Sampang assets decline
Maari production improved after the MR3 workover, averaging 4,919 barrels a day in September, and the next lifting has been sold at a record premium to Dated Brent, according to Cue. However, a seawater injection flowline remains offline after an integrity issue was identified. Oil production has continued, while the operator assesses options to reinstate injection.
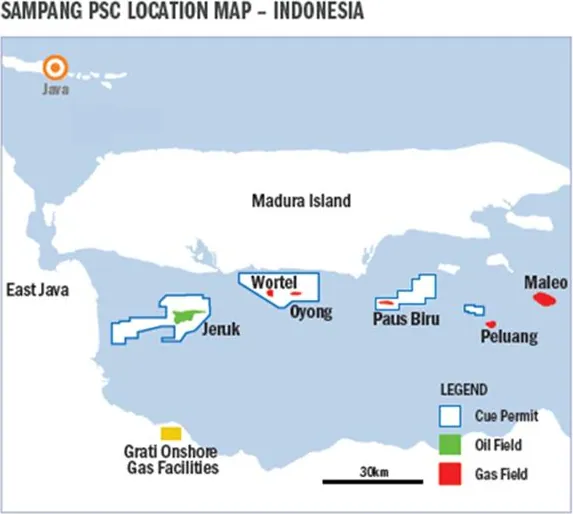
Sampang remains a more defensive part of the portfolio. Production from its mature Oyong and Wortel gas fields continued to decline, although compression work at the Grati processing plant lifted gross gas sales from 5.3 TJ a day in July to about 6.6 TJ a day in September. Cue still expects to exit the permit when it expires in December 2027 and is progressing decommissioning planning.
Sixth dividend adds to shareholder returns
Cue paid its sixth consecutive dividend in October, returning a further A$1.75 million to shareholders and taking cumulative cash distributions since 2024 to A$35 million. The payment comes after FY2026 revenue of A$50.3 million and underlying EBITDAX of A$28.5 million, while Horizon Oil’s acquisition of a 57.03% interest in Cue has reshaped the board.
Richard Malcolm intends to retire as a non-executive director at the 12 November annual meeting. The immediate operating questions are more concrete: whether PB-42 sustains its initial rate, how PV14 performs once evaluated, and whether approvals and land access allow Mahato’s next phase and GA-1 to move from plans into activity.
Get ASX:CUE news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Cue enters FY2027 with stronger cash generation and several development catalysts, but the headline production decline and unresolved asset-life issues make execution more important than the quarter’s oil-price lift.
Questions in the middle?
- Can PB-42 maintain its 520 bopd gross initial rate as further Mahato wells and workovers come online?
- Will PV14’s evaluated flow performance support the expected Palm Valley supply program, and can PV15 reach total depth on schedule?
- How quickly will Mahato’s OPL3 approvals and GA-1 land access be resolved, and what capital demands will follow?
Sources
1-
Quarterly Activities Report (opens in a new tab)Verified company source. Cue Energy Resources Limited · 29 Oct 2026 · cuenrg.com.au