Turaco locks in funding to consolidate Afema gold project

Turaco Gold has secured firm commitments for a A$120 million placement to fund its proposed acquisition of Afema’s remaining 20% interest and push the Côte d’Ivoire project towards a definitive feasibility study. The transaction would simplify ownership, but still depends on shareholder approval and further development funding.
- A$120 million institutional placement at A$0.60 a share
- Share purchase plan aims to raise a further A$10 million
- Proposed acquisition values Afema’s remaining 20% at US$79 million
- Afema hosts a 4.65Moz resource and 1.91Moz probable reserve
- Acquisition and conditional placement tranche require shareholder approval
 Add us as a preferred source on Google
A$120 million placement funds Afema consolidation
Turaco Gold (ASX:TCG) has raised the money needed to pursue full control of its flagship Afema gold project, securing firm commitments for a A$120 million institutional placement at A$0.60 a share. The company also intends to raise up to A$10 million through a share purchase plan, taking the proposed equity financing to A$130 million.
The placement was supported by existing institutional investors, a leading global long-only resources fund and select new international institutions. Its price represents a 12.4% discount to Turaco’s 26 October closing price of A$0.685 and a 13.1% discount to the five-day VWAP of A$0.690.
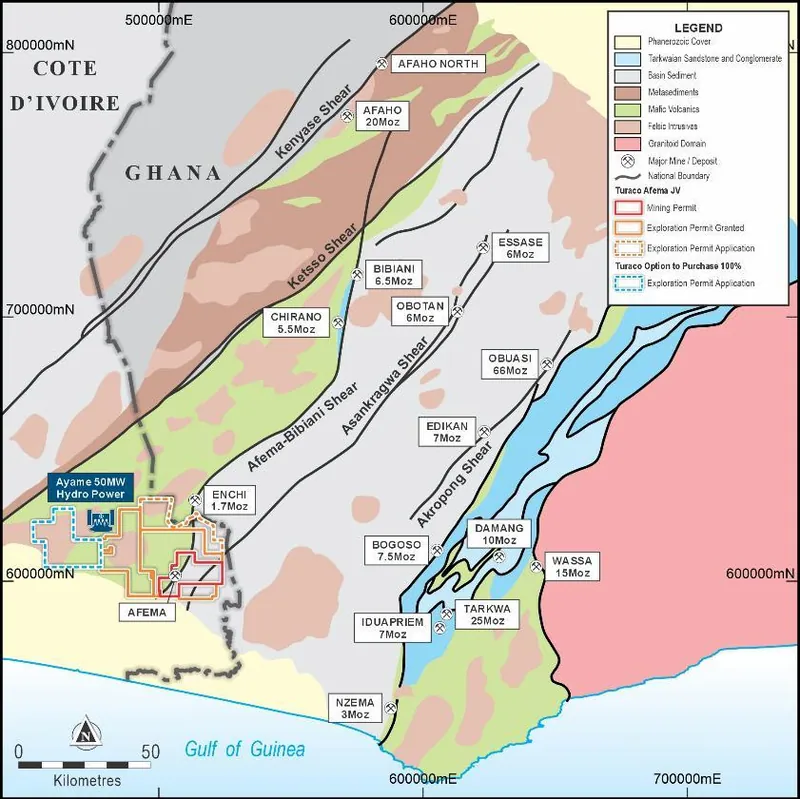
The funding follows Turaco’s agreement to acquire Sodim’s remaining 20% interest in Afema, a transaction that would leave Turaco with 100% project ownership subject to the Côte d’Ivoire Government’s 10% non-contributing interest. The proposed purchase is valued at about US$79 million, or A$112 million, including cash, shares, options and the previously paid option fee.
Ownership structure shifts ahead of project financing
Turaco has paid Sodim a non-refundable US$3 million fee for a three-month option. If exercised, the acquisition would require US$30 million in cash, the issue of 55.1 million Turaco shares and 36.7 million options. The shares would be subject to a 12-month voluntary escrow, while the options would expire after three years, with exercise prices of A$1.00 and A$1.20 across two tranches.
The deal would end Sodim’s existing right to contribute to development or convert its interest into a 1.5% net smelter royalty at a decision to mine. Sodim would instead retain a 0.33% royalty, which Turaco intends to buy back for US$12.5 million before 30 June 2027. The parties would also forgo about US$24 million of historical project expenditure otherwise repayable from Sodim’s share of project cash flow, along with an existing discovery payment of up to US$2.5 million.
Turaco says the consideration compares with an implied look-through value of about A$173 million for the acquired interest, based on its market metrics. The company’s calculation also places the purchase at 0.16 times the attributable Afema NPV based on the June 2026 pre-feasibility study, which assumed a gold price of US$4,000 an ounce. Those comparisons are company-derived and depend on the underlying study assumptions, including funding, gold prices and the eventual cost of building the mine.
Afema carries a large resource and ambitious production plan
Afema’s current JORC Mineral Resource stands at 4.65 million ounces from 116.7 million tonnes grading 1.3 grams per tonne, while its open-pit Probable Ore Reserve is 1.91 million ounces. The pre-feasibility study outlined average production of 215,000 ounces a year in the first seven years and a mine life of more than 10 years.
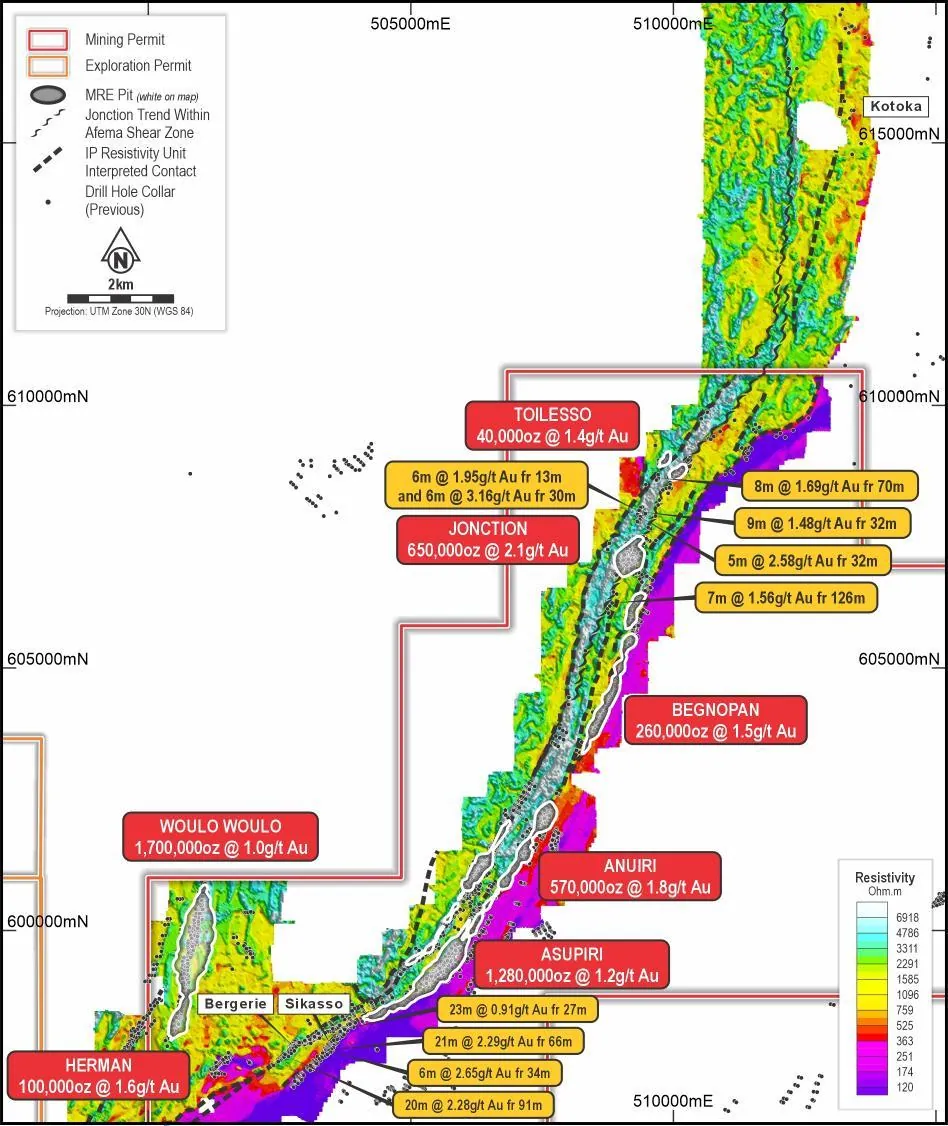
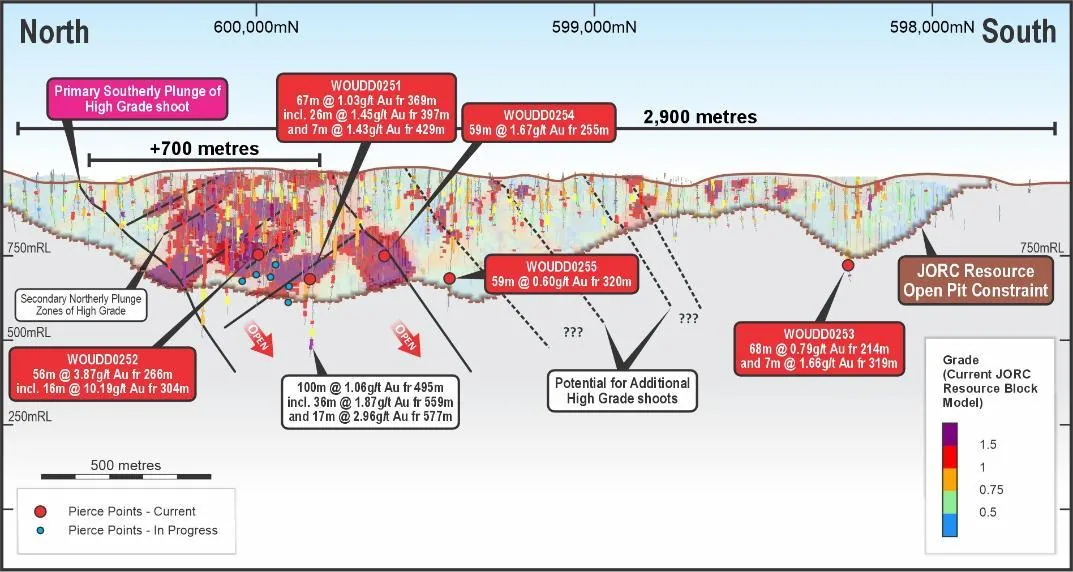
Recent exploration has continued to feed the project’s growth narrative. Turaco’s October Woulo Woulo drilling reported a 56-metre intersection grading 3.87 grams per tonne, including 16 metres at 10.19 grams per tonne, beneath the existing resource and open-pit design. The company expects another Mineral Resource update in the fourth quarter of 2026.
The new capital is earmarked for detailed engineering, early development work, exploration, the expected royalty buyback and a definitive feasibility study targeted for the second quarter of calendar 2027. Turaco is also pursuing debt financing in parallel, but the company acknowledges that the project’s estimated US$410 million development cost, plus US$32 million of pre-production mining, will require substantial funding beyond this raise.
Shareholder vote remains the immediate gate
The acquisition is not complete. Turaco needs shareholder approval to issue Sodim’s consideration securities, while the A$23 million second tranche of the placement also requires approval at an extraordinary general meeting expected in early December. If approval for the acquisition is not obtained within the option period, the US$3 million option fee will not be refunded.
Assuming the placement, share purchase plan and acquisition proceed, Turaco expects pro forma cash of roughly A$125 million after the acquisition cash payments. That balance is intended to carry the company through pre-FID work and the DFS, not to finance construction. The next test is therefore less about whether Afema can be consolidated than whether the enlarged Turaco can convert a compelling study into a financeable development without another heavily dilutive capital call.
Get ASX:TCG news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The raise removes an immediate funding hurdle, but Afema still needs shareholder approval, a definitive feasibility study and a much larger construction financing package before its production case can be tested in practice.
Questions in the middle?
- Will shareholders approve the consideration securities and conditional placement tranche in December?
- Can the next Mineral Resource update convert current exploration momentum into additional mineable ounces?
- What mix of debt and future equity will fund Afema’s estimated US$410 million development cost?
Sources
2-
Consolidation of Afema Ownership Presentation (opens in a new tab)Verified source. Turaco Gold Limited · 29 Oct 2026
-
Equity Financing to Consolidate Afema Ownership (opens in a new tab)Verified source. Turaco Gold Limited · 29 Oct 2026