Central Petroleum faces cash and production pressure after weak PV14 start

Central Petroleum’s first new Palm Valley well is producing around 0.5 TJ/d, well below pre-completion expectations of 3-4 TJ/d, with water loading a possible cause. Cash fell to $14.9 million as drilling costs rose, leaving the company reliant on a planned clean-out and the next well, PV15, to restore momentum.
- PV14 flowing at around 0.5 TJ/d versus pre-completion expectations of 3-4 TJ/d
- PV14 clean-out planned within a month, subject to joint venture approval
- September-quarter sales revenue of $10.8 million, broadly stable quarter on quarter
- Cash declined to $14.9 million after $7.8 million of exploration and appraisal spending
- PV15 drilling reached 1,102 metres and could come online by late December if successful
 Add us as a preferred source on Google
PV14 flow rate falls short after production start
Central Petroleum Limited (ASX:CTP) has started selling gas from PV14, but the first well in its Palm Valley drilling program is producing at only around 0.5 TJ/d. That is materially below the 3-4 TJ/d indicated by pre-completion flow tests, with Central saying water loading may be restricting the well.
The company plans to clean out PV14 within the next month, subject to joint venture approval. Until that work is complete, Central said it cannot confidently assess the well’s sustainable production rate. The result extends the uncertainty flagged in the earlier PV14 water risk update, which reported water during vacuum flow and an initial test below the company’s target.
PV15 advances while Palm Valley capacity remains conditional
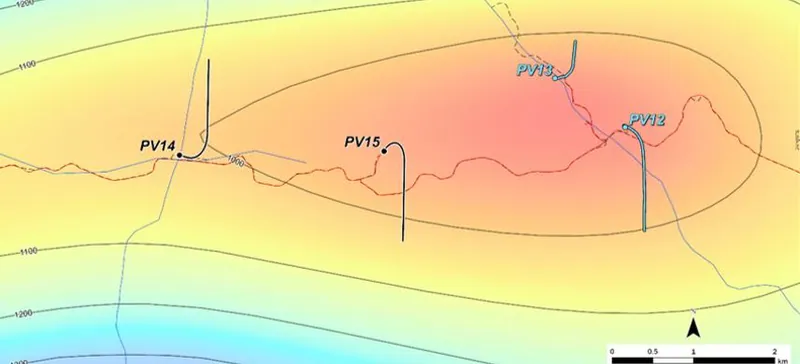
The second well, PV15, spudded on 18 October and had reached 1,102 metres measured depth by 30 October, against a planned depth of 3,114 metres. It is located 2.3 kilometres from PV14 and targets the southern flank of the Palm Valley anticline, closer to the field crest and further up-dip from possible water sources than PV14.
If successful, PV15 is expected to come online by the end of December 2026. Central has said the two-well program could move Palm Valley production capacity towards the field’s 14 TJ/d plant capacity, but that prospect now depends on both PV15 drilling and the outcome of the PV14 clean-out. The program was originally framed as supporting a roughly 40% Palm Valley capacity increase.
Stable gas revenue masks heavier drilling spend
September-quarter sales revenue was $10.8 million, down 1% from the June quarter. Gas revenue was essentially unchanged at $10.7 million: sales volumes rose 1% to 1.0 PJ, while the average realised gas price slipped 1% to $10.28 per gigajoule because of the contract delivery mix.
Oil revenue fell to $84,000 after Mereenie oil sales were suspended indefinitely following a July lifting and revised oil specification requirements. Central is pursuing alternative sales arrangements, but the filing gives no timing for a restart. Mereenie gas sales averaged 25.9 TJ/d on a gross basis, while Palm Valley production held steady at 5.6 TJ/d.
Cash declines as PV14 absorbs $7.1 million
Cash fell from $20.4 million at 30 June to $14.9 million at 30 September. Exploration and appraisal expenditure reached $7.8 million, including $7.1 million for PV14 mobilisation and drilling, while capital expenditure added another $1.9 million for surface facilities and sustaining work.
Net cash used in operating activities was $3.5 million. Central said the end of payments for previously overlifted gas reduced gas purchase costs by $1.7 million, although annual staff incentives and accumulated staff cost recoveries from joint ventures offset part of that benefit. Net debt stood at $11.25 million at quarter end, with quarterly loan interest capitalised into the balance.
Funding window narrows ahead of debt repayments
Central reported $16.7 million of undrawn debt capacity and estimated nine quarters of funding based on its cash balance and available facilities. That calculation is not a forecast of future production or spending, and the unused facility availability expires on 31 December 2026. Principal repayments on the secured Macquarie Bank loan begin in March 2027, while the reported floating interest rate was 12.8215% at quarter end.
The company also recorded a minor spill of about 75 barrels of drilling fluid at the PV14 site, although it said no long-term environmental impact was anticipated. The immediate operational test is more consequential: whether the clean-out can lift PV14 materially, and whether PV15 avoids the water-related problem that has clouded the first well.
Get ASX:CTP news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
PV14’s clean-out and PV15’s drilling result are now the key tests of whether Palm Valley investment can translate into higher production before debt repayments begin.
Questions in the middle?
- Can the planned PV14 clean-out restore production towards the pre-completion flow-test range?
- Will PV15 confirm a more productive, less water-affected part of the Palm Valley structure?
- How will cash use and the expiry of undrawn funding capacity affect Central’s position before loan repayments start in March 2027?
Sources
1-
Quarterly Activities Report & Appendix 5B (opens in a new tab)Verified source. Central Petroleum Limited · 30 Oct 2026