A$1.85 million cash and a 12,000tpa Thai plant target

5 min read
5:46pm on Friday 30th of October, 2026 AEDT ~5pm, 30th Oct, 26
Hastings Technology Metals has completed its 49% Thai processing plant acquisition and is targeting first mixed rare earth chloride production in the June 2027 quarter. But the company ended September with A$1.85 million in cash, leaving funding the immediate test for both its downstream strategy and Yangibana development.
- 49% Kabin Buri plant acquisition completed for consideration capped at US$15 million
- First Thai MREC production targeted for Q2 CY2027 at approximately 12,000 tonnes per annum
- Yangibana Stage 1 DFS shows A$649 million pre-tax NPV and 34% IRR
- Yangibana requires approximately A$333.4 million of initial capital before FID
- Cash fell to A$1.85 million, equivalent to about 1.53 quarters of reported funding
 Add us as a preferred source on Google
Thai plant moves from transaction to commissioning
Hastings Technology Metals Ltd (ASX:HAS) has moved its Thai rare earths strategy into the execution phase, completing the acquisition of a 49% interest in the Kabin Buri hydrometallurgical plant after the quarter ended. The facility is being upgraded towards approximately 12,000 tonnes per annum of mixed rare earth chloride, with first production targeted for the June 2027 quarter, subject to completion of the works and successful commissioning.
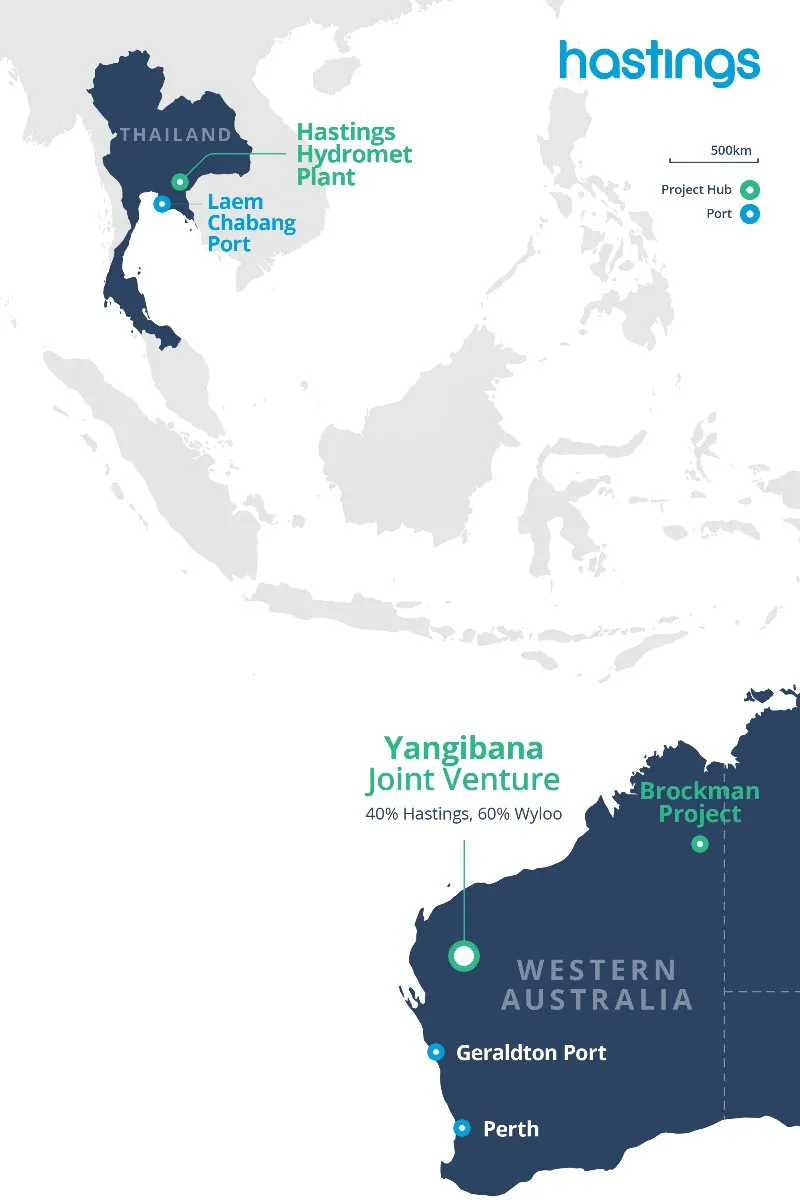
The consideration remains capped at US$15 million. It includes US$8 million of equity consideration, a US$1 million commissioning payment and US$5.5 million of deferred cash payments linked to future production and sales performance. Hastings is also required to issue 23 million shares to Enuo Holdings at A$0.50 each. The shares are expected to represent about 9% of the enlarged capital and cannot be transferred for six months without Hastings’ consent. The transaction had been completed by the time of the company’s 28 October announcement, covered in the Thai plant acquisition.
Commissioning now carries the operational burden
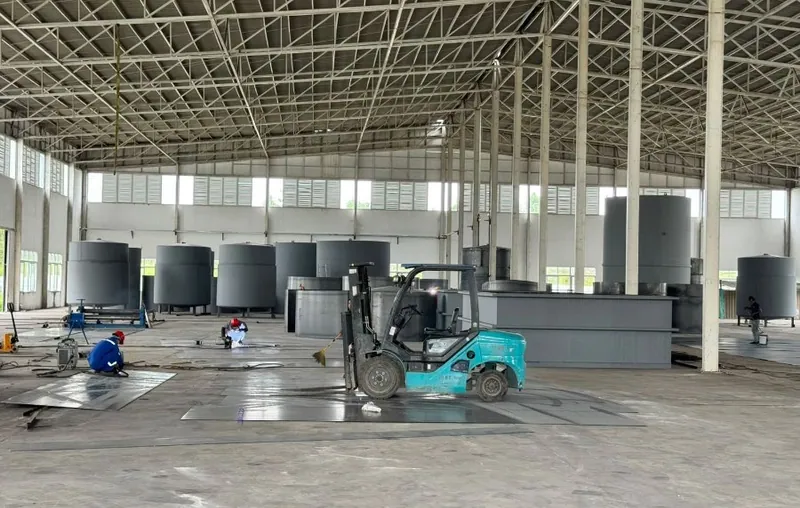
During the September quarter, Hastings spent A$1.10 million on operational readiness, with tank welding, fabrication and process-vessel handling continuing at the site. A binding agreement with Enuo covers at least 10,000 tonnes per annum of African-sourced monazite concentrate, meaning the plant’s initial operations are not dependent on Yangibana feedstock. The company said it had also received enquiries from prospective feedstock suppliers and MREC customers across the United States, Europe and Asia, although no customer contracts were disclosed in this report.
Hastings plans to complete installation and upgrade work before testing and commissioning. It is preparing an application for investment promotion through Thailand’s Board of Investment and negotiating with BZNM’s other shareholders to increase its stake to 51% or more. Any move to majority ownership remains subject to agreement and regulatory approvals.
Yangibana economics remain strong on paper
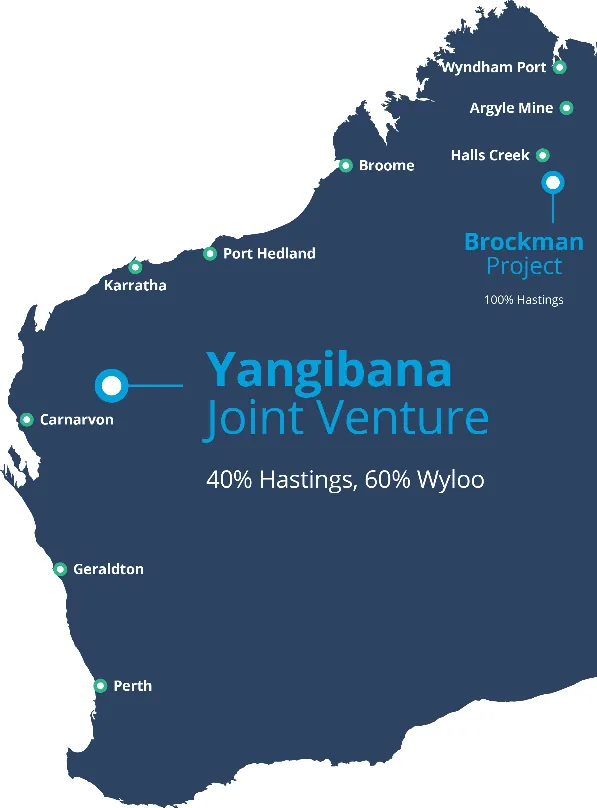
At Yangibana, the updated Stage 1 definitive feasibility study continues to present an attractive project case: a pre-tax ungeared NPV8 of A$649 million, a 34% pre-tax ungeared IRR and a 2.4-year payback on initial capital of A$333.4 million, all on a 100% project basis. Hastings’ 40% share of the initial capital would be approximately A$133 million. The study assumes a 19-year mine life based entirely on a 20.93 million tonne Proved and Probable Ore Reserve, with no Inferred Resources included, as detailed in the Yangibana Stage 1 DFS.
The project is not yet financed. The Yangibana joint venture intends to seek project-level debt with a target minimum gearing of 50%, while Hastings is assessing strategic investment, government-backed finance and other funding options for its share. No binding financing arrangements have been entered into, and no Final Investment Decision can occur until funding is secured. Wyloo’s process to sell its 60% interest is also ongoing, with no binding agreement announced at the report date.
Cash runway sharpens the funding question
Hastings ended September with A$1.85 million in cash, down from A$3.71 million at the end of June. Operating activities used A$1.14 million during the quarter, while investing activities used A$1.56 million, partly offset by A$843,000 of net financing inflows from the August placement. On the company’s reported calculation, available funding covered approximately 1.53 quarters of relevant outgoings.
Hastings said it expects operating cash outflows to remain broadly consistent in the near term and plans to pursue equity, debt and strategic funding, while considering sales of non-core assets. It also warned that progress at both the Thai plant and Yangibana depends on securing additional funding within the required timeframe. The next meaningful markers are therefore practical rather than promotional: completion of Thai installation works, commissioning, evidence of feedstock and customer conversion, and a financing pathway capable of taking Yangibana to FID.
Get ASX:HAS news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The Thai plant offers Hastings a nearer-term production route, but commissioning costs and Yangibana’s much larger capital requirement arrive against a cash balance that covers little more than one and a half quarters of reported outgoings.
Questions in the middle?
- Can Hastings complete commissioning and reach first MREC production in Q2 CY2027 without a further material funding event?
- What funding structure will support Hastings’ share of Yangibana’s approximately A$333.4 million Stage 1 capital requirement?
- Will Wyloo’s sale process change Yangibana’s ownership, financing timetable or path to Final Investment Decision?
Sources
1-
Quarterly Activities/Appendix 5B Cash Flow Report (opens in a new tab)Verified source. Hastings Technology Metals Ltd · 30 Oct 2026