Sigma Lithium buys time with US$100m bond as operations restart

Sigma Lithium has launched a US$100 million convertible bond to replace expensive secured debt and push its main repayment risk into 2029 and 2031. The financing arrives as operations recover from a Brazilian suspension that cut third-quarter production but left the company reporting a 32% gross margin.
- US$100m five-year unsecured convertible bond due 2031
- Fixed 7.00% coupon replaces 11.45% floating-rate secured debt
- Short-term debt expected to fall by about 80% after refinancing
- Third-quarter production fell to 7,293 tonnes after operational stoppages
- FY26 AISC guidance reduced 6% to US$668/t
 Add us as a preferred source on Google
Convertible bond pushes Sigma’s main debt risk into 2029 and 2031
Sigma Lithium Corporation (ASX:SAU) is attempting to trade near-term financing pressure for a longer runway, announcing a US$100 million five-year senior unsecured convertible bond. Net proceeds are intended to repay its senior secured debt with Synergy Capital, moving the bond’s final maturity to approximately November 2031 and reducing the company’s short-term debt by about 80% on a pro forma basis.
The refinancing would also replace Synergy’s floating rate of SOFR plus 6.95% with a fixed 7.00% coupon. That is a lower stated cash rate, while the switch from secured to unsecured borrowing would release the security attached to the existing facility. Bondholders would have an investor put at the end of year three, around November 2029, so the liability is deferred rather than eliminated.
Operations recover after Brazilian licence dispute
The funding announcement comes alongside a preliminary, unaudited preview of a difficult third quarter. Sigma produced 7,293 tonnes of lithium oxide concentrate after local authorities suspended operations during the quarter, while gross revenue fell 23% year on year to US$23 million. Yet the company maintained a 32% gross margin and reported a CIF China cash cost of US$518 per tonne, 5% below the comparable quarter despite the lower production base.
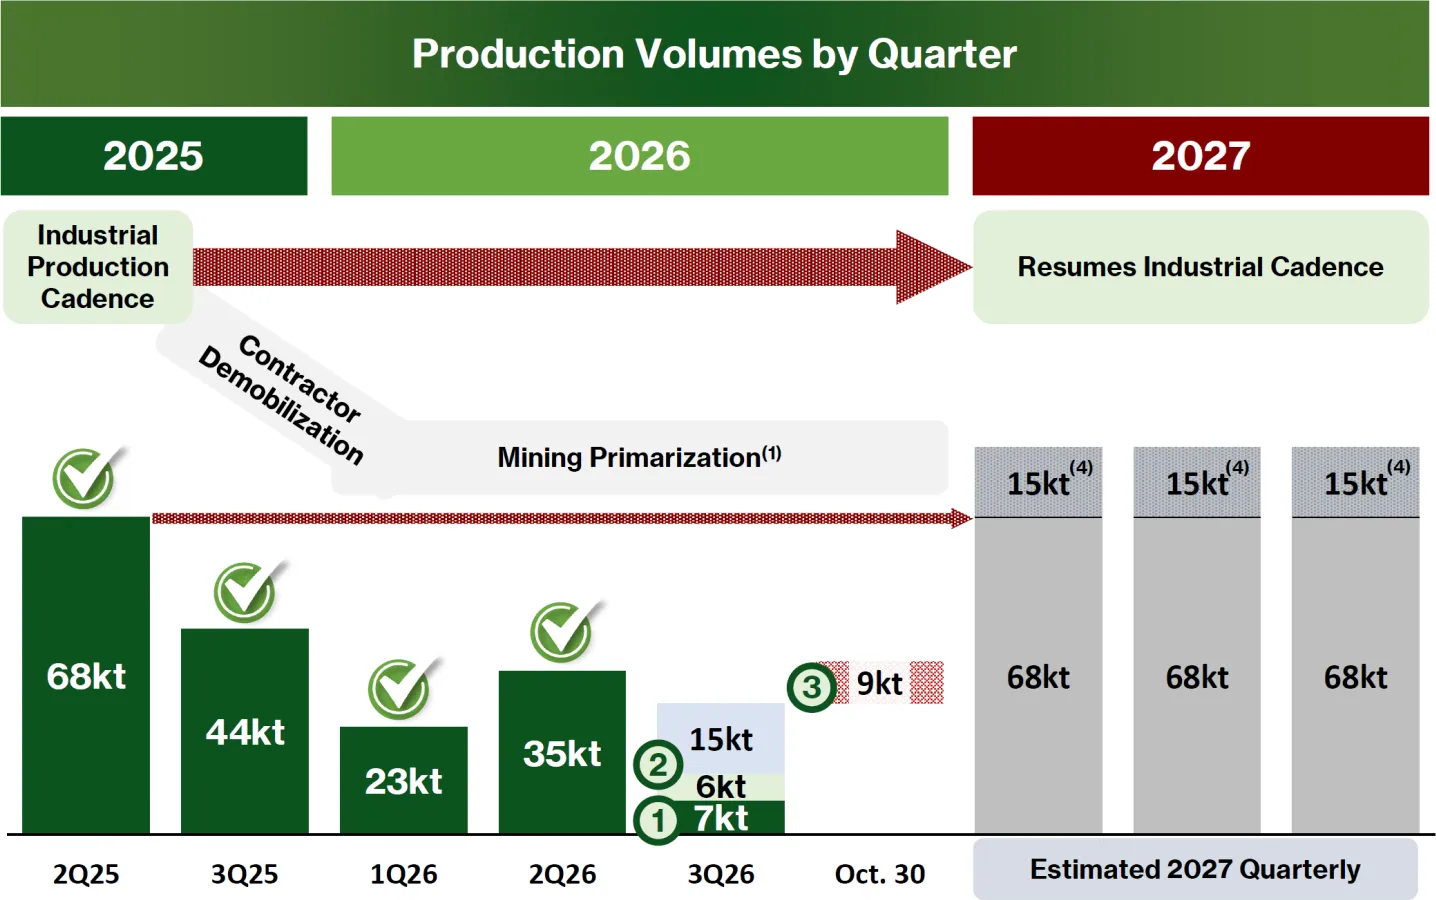
Operations restarted early in the fourth quarter after State and Federal Court protection for the company’s operating and mining licences. That restart followed the court-backed licence restoration, which earlier enabled mining and processing to resume. Sigma says it has produced 9,000 tonnes of high-grade concentrate since restarting to October 30, with another 21,000 tonnes of third-quarter inventory available for sale, including 15,000 tonnes of low-grade material and 6,000 tonnes of intermediate products.
Lower cost guidance meets a thin cash position
Sigma cut FY26 all-in sustaining cost guidance by 6% to US$668 per tonne, while retaining its FY27 guidance of US$620 per tonne and production target of 330,000 tonnes from Plant 1. The company expects 240,000 tonnes over the next 12 months, although those figures remain dependent on the operating restart continuing as planned and are forward-looking estimates rather than achieved production.
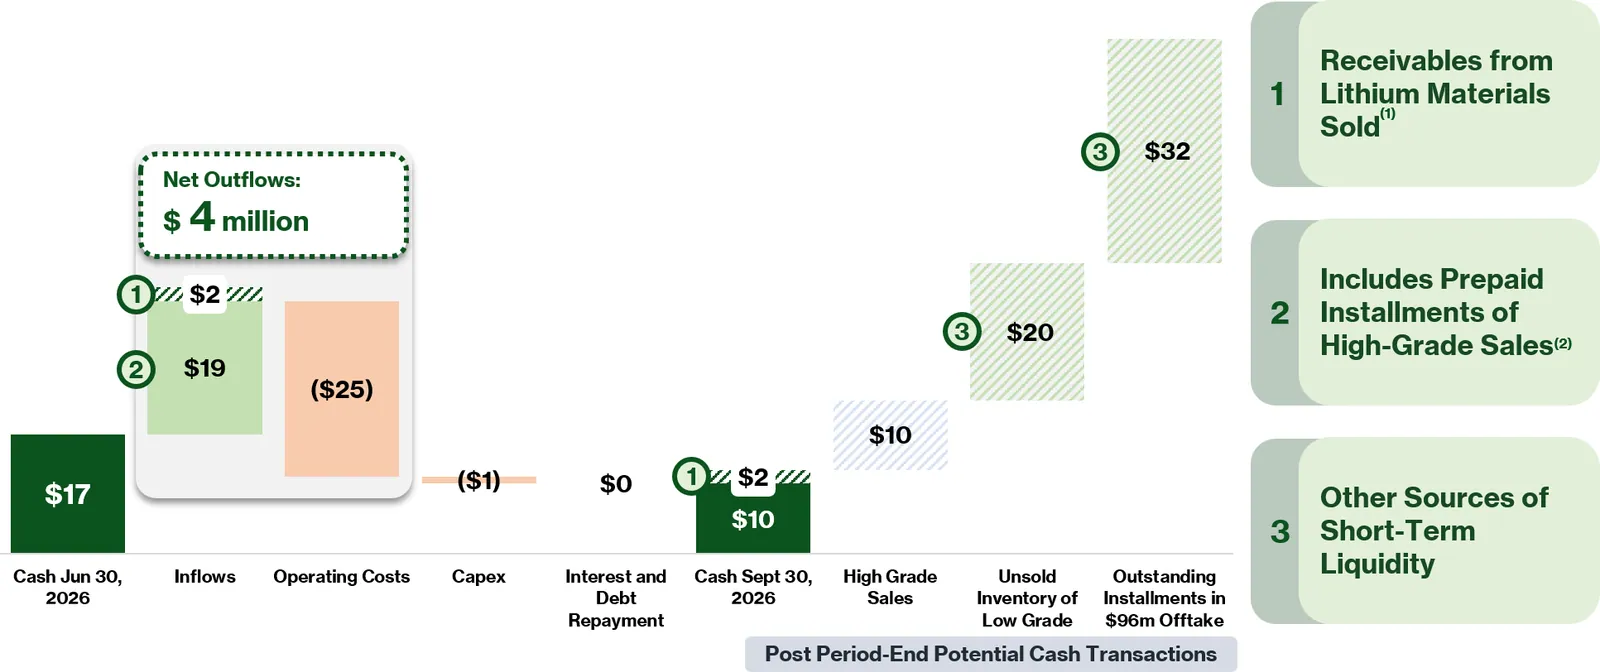
The balance sheet remains the less comfortable part of the picture. Cash and equivalents stood at US$10 million at September 30, while Sigma identified up to US$62 million of potential short-term liquidity from receivables, unsold low-grade inventory and remaining offtake instalments. The timing and value of those inflows depend on sales and lithium prices. The bond offering is also not yet the same as cash in the bank: it remains subject to pricing, closing and required approvals.
Conversion terms leave a future dilution question
The bonds are convertible into CHESS Depositary Interests at a 25% premium to the reference share price, with conversion unavailable during the first 12 months except in limited circumstances. That gives Sigma a route to reduce debt later, but conversion would increase the number of shares on issue. The remaining proceeds after repaying Synergy are earmarked for growth capital expenditure and general corporate purposes, including the company’s planned expansion ambitions.
Get ASX:SAU news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The refinancing could buy Sigma time and reduce cash interest costs, but investors still need to see the bond close, operations stabilise and liquidity convert into cash receipts.
Questions in the middle?
- Will the US$100 million bond close on the proposed terms and fully repay the Synergy facility?
- Can Sigma turn its 21,000 tonnes of available inventory and offtake instalments into cash before liquidity tightens?
- How much dilution could arise if bondholders exercise the 25%-premium conversion feature?
Sources
2-
Previews 3Q26 Results- 9,000T Produced Since Restart (opens in a new tab)Verified company source. Sigma Lithium Corporation · 3 Nov 2026 · sigmalithiumcorp.com
-
US$100m Convertible Bonds to Refinance Secured Debt (opens in a new tab)Verified company source. Sigma Lithium Corporation · 3 Nov 2026 · sigmalithiumcorp.com